Accepting Card Payments for the First Time: UK Guide (2026)
22 September 2026 · 14 min read
According to UK Finance, cash transactions have dropped to a mere 8% of all UK payments. If you are accepting card payments for the first time UK trading realities demand a fast, modern checkout, yet legacy acquirers continue to push complex jargon, costly terminal leases, and unexpected compliance penalties. It's completely natural to feel cautious. Between equipment rental commitments, rolling fees, and lengthy settlement cycles that freeze your working capital, taking card payments often feels unnecessarily risky. You shouldn't have to surrender your hard-earned margins just to give customers the checkout options they expect.
Modern payment processing shouldn't tie your hands. This guide shows you how to set up card payments seamlessly for your UK business whilst avoiding hidden fees and lengthy contracts. We'll demystify merchant accounts, identify the exact hardware you need on the counter, and show you how next-day settlement keeps your cash flow moving. You will discover how to start accepting contactless, chip and PIN, and mobile wallets reliably within days.
Key Takeaways
- Master the basics of card infrastructure so you can separate genuine processing charges from punitive terminal leasing schemes.
- Avoid restrictive multi-year equipment contracts by choosing transparent providers that remove monthly hardware hire fees entirely.
- Protect your daily operating liquidity by insisting on standard next-day payouts rather than enduring multi-day clearing cycles.
- Follow our structured checklist for accepting card payments for the first time UK wide, ensuring effortless onboarding without operational downtime.
- Discover how modern all-in-one solutions deliver enterprise-grade card machines and straightforward fixed rates from your very first trade.
Why UK Small Businesses Must Accept Card Payments in 2026
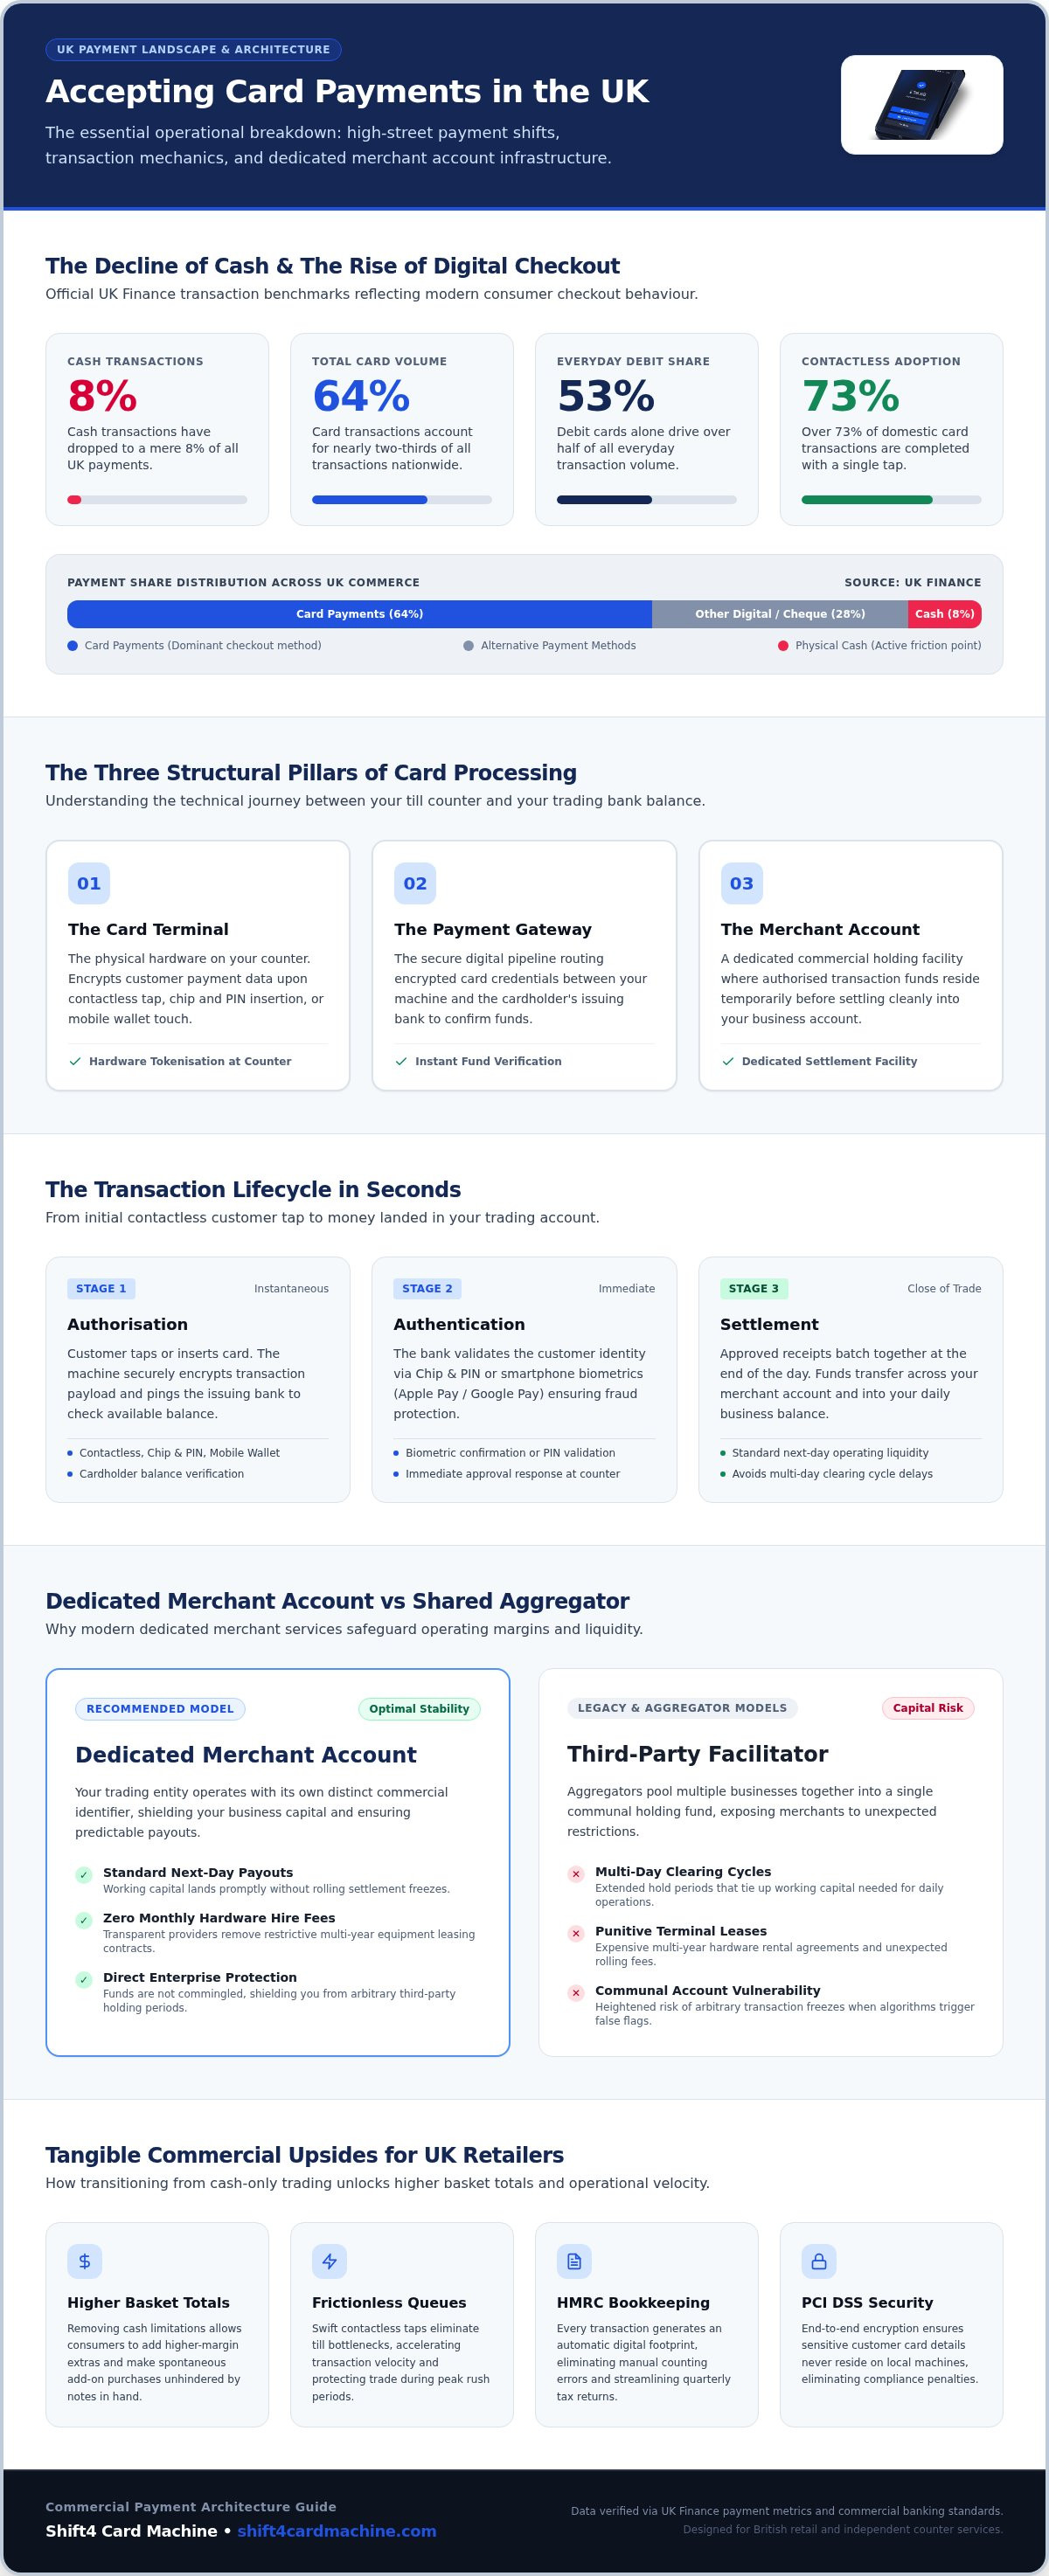
Cash is no longer king on the British high street. UK Finance reports that card transactions account for 64% of all UK payments, with debit cards alone driving 53% of all everyday volume. Operating a cash-only business is no longer a traditional charm; it is an active barrier between your counter and your customers. When considering accepting card payments for the first time UK merchants must recognise that digital transactions are an absolute operational baseline. Without a card machine, you turn away genuine revenue every working day.
Beyond capturing immediate sales, card processing builds complete financial transparency. Every tap or dip automatically records a digital footprint. This creates effortless, automated transaction logs that simplify your bookkeeping and streamline your HMRC compliance, saving you hours of manual reconciliation at the end of each tax quarter.
The Rapid Transition to a Cashless Society
UK consumer habits have fundamentally transformed. Over 73% of all domestic card transactions are contactless, driven by everyday purchases where shoppers simply tap their card or smartphone and walk away. Finding a working, free-to-use ATM has become increasingly difficult as high-street bank branches close. Shoppers rarely carry notes; asking a prospective buyer to track down cash almost always ends with an abandoned basket.
Customer Expectations and Revenue Growth
Payment flexibility directly expands transaction values. When shoppers are constrained by physical cash, their purchase stops at the bank notes in their wallet. Digital payments remove that friction. Customers routinely add higher-margin extras, browse premium ranges, and make spontaneous decisions when they know they can pay securely via chip and PIN or digital wallets.
- Instant Credibility: Supporting Apple Pay and Google Pay signals that your business is secure, professional, and modern.
- Higher Basket Totals: Removing cash constraints allows consumers to complete unplanned, spontaneous add-on purchases.
- Frictionless Checkouts: Swift card taps eliminate queues, speed up turnover, and keep trade flowing during busy peak periods.
Understanding the underlying infrastructure, including how merchant accounts work to settle customer card funds securely into your business, helps demystify the entire transition. For any retailer or trade professional accepting card payments for the first time UK wide, the commercial upside is clear: higher average spend, happier customers, and total protection against lost footfall.
How Card Processing Works: Key Terminology Demystified
Card transactions often sound like an impenetrable maze of banking jargon. In reality, the technical journey is clean and fast. When accepting card payments for the first time UK business owners only need to understand three core components: the physical card machine, the payment gateway, and the merchant account. Together, these systems authenticate customer funds and transfer them directly into your trading balance.
Merchant Accounts vs Direct Payment Facilitators
A merchant account is a specialised commercial holding account. It temporarily holds card receipts before depositing them into your standard business bank account. Third-party payment aggregators pool your money into a shared communal account, leaving you vulnerable to sudden account freezes or arbitrary holding periods. In contrast, a dedicated merchant account grants complete operational stability, fee transparency, and faster settlements. Explore our guide on merchant services UK no monthly fee to see how dedicated accounts protect your daily margins.
The Lifecycle of a Card Transaction
Every transaction completes in seconds across three coordinated stages:
- Authorisation: The customer taps or inserts their card. The machine encrypts the data and contacts the cardholder's bank to verify available funds.
- Authentication: The bank confirms security credentials via Chip and PIN or biometric smartphone approval.
- Settlement: Approved transactions are batched at close of trade. Funds move through your merchant account, then land directly in your bank account.
Security Standards and PCI Compliance Basics
Security is non-negotiable. The Payment Card Industry Data Security Standard (PCI DSS) governs how businesses handle sensitive cardholder data. Modern card machines eliminate compliance anxiety by using end-to-end encryption and hardware tokenisation right at the counter. Sensitive details never touch your local computer network. This protects you against transaction disputes, chargebacks, and fraud risks, ensuring complete peace of mind while accepting card payments for the first time UK wide. If you want dependable security paired with seamless setup, look at how Shift4 Card Machine delivers robust merchant account integration from day one.
Understanding Fees, Terminal Contracts, and Payout Schedules
Card payment pricing shouldn't require an accounting degree to decipher. For business owners accepting card payments for the first time UK provider contracts often conceal punitive charges beneath attractive headline marketing. Knowing how acquirers charge for hardware, manage transaction percentages, and schedule payouts is essential to safeguard your trading margins.
Uncovering Hidden Charges in Terminal Agreements
Traditional merchant agreements routinely disguise ongoing costs behind complex paperwork. The Payment Systems Regulator introduced Specific Direction 16 to curb predatory long-term terminal leases, yet many legacy providers still impose unnecessary overheads. Watch out for these common contract traps:
- Monthly Terminal Hire: Recurring rental charges that outstrip the physical hardware's value over time.
- Minimum Monthly Service Charges (MMSC): Penalties charged if your monthly processing volume falls below an arbitrary threshold.
- PCI Non-Compliance Levies: Recurring administrative fees billed if self-assessment paperwork is not submitted promptly.
- Setup and Authorisation Fees: Additional charges tacked onto every single transaction batch.
Evaluating Transaction Fee Structures
Processing charges generally follow two models: interchange-plus or fixed flat rates. Interchange-plus calculates card scheme fees, bank interchange, and processor markup separately for every tap. While detailed, it creates unpredictable monthly statements. In contrast, a transparent flat-rate model applies one clear percentage across all accepted cards, making budgeting straightforward. Compare independent plans via our guide to the best card machines for UK small businesses to find terms suited to your trade.
The Critical Value of Next-Day Settlement
Transaction fees are only half the commercial equation. Payout speed directly dictates your cash flow. Traditional banking clearing cycles can lock up your revenue for three to five working days. Waiting days for your own trading money puts immense pressure on supplier orders, payroll, and stock replenishment.
Modern card infrastructure changes this dynamic. Standard next-day settlement ensures today's card takings arrive in your bank account the very next working day. When accepting card payments for the first time UK founders need that liquidity to reinvest immediately. Read our breakdown of card machine next day payout systems to see how fast clearing protects operational stability.
Five Steps to Accepting Your First Card Payment
Setting up your business to take digital payments should never be intimidating. When accepting card payments for the first time UK owners often worry about complicated IT configurations or stalled applications. Following a clear, structured sequence ensures you move from unboxing your hardware to ringing up customer sales without a hitch.
Step 1 & 2: Terminal Selection and Document Preparation
First, evaluate how your trade moves. If customers pay at a counter, a compact terminal works well. If you seat guests or visit client premises, prioritise a standalone unit with a built-in printer and mobile SIM. Next, prepare your standard verification documents to speed through UK anti-money laundering regulations:
- Proof of Identity: A valid UK passport or full photocard driving licence.
- Proof of Address: A utility bill or bank statement dated within the last three months.
- Trading Details: Proof of an active UK commercial bank account and company registration details if trading as a limited company.
Step 3 & 4: Hardware Setup and Connectivity Configuration
Once approved, modern standalone hardware arrives ready for immediate action out of the box. Power on the terminal. Connect to your premises Wi-Fi or rely on the pre-installed cellular 4G SIM for instant data access. Take five minutes to configure your merchant preferences. You can toggle optional gratuity screens, enable custom receipts, and train your staff on basic refund or cancellation workflows.
Step 5: Processing the First Transaction and Reconciling
Complete a live test before welcoming paying customers. Enter a nominal amount like £1.00 on the keypad. Tap a debit card or smartphone wallet against the reader to confirm instant authorisation. Once the approval prints or displays, test a quick void or refund to ensure your end-of-day audit balances perfectly. At closing, generate an automated batch report directly on the device. Check that your physical takings reconcile precisely against your pending merchant payouts.
Completing these steps gives you total control over your till. For any business accepting card payments for the first time UK compliance checks, network pairing, and initial test runs are quick milestones that unlock faster customer turnover and reliable daily cash flow.
Start Taking Payments with the Shift4 OneCard Solution
Modern card acquiring should empower your venture rather than drain its operating budget. If you are accepting card payments for the first time UK banking institutions often attempt to lock you into costly monthly terminal rentals and confusing sliding scales. Shift4 Card Machine replaces that outdated model with total transparency, providing enterprise-grade payment infrastructure designed specifically for ambitious British enterprises.
No Terminal Rental Fees and Transparent Rates
Draining your monthly cash flow with ongoing equipment hire simply doesn't make sense. With Shift4, there are zero monthly terminal rental charges. Instead of facing complex rate sheets and surprise admin fees, you benefit from a straightforward, fixed 0.85% transaction fee across credit and debit cards. That clarity protects your profit margins on every sale. Review our comprehensive Shift4 OneCard guide to explore the full technical specifications and commercial features.
Robust Hardware Built for Busy Trading
Fast checkouts demand dependable technology that never falters. The Shift4 OneCard terminal is an ergonomic, standalone powerhouse engineered for high-volume retail, hospitality, and mobile services. Dual-connectivity ensures you never miss a sale: the machine switches automatically between premises Wi-Fi and built-in roaming 4G cellular data. You can take payments at the counter, at tables, or out on the road without needing a separate smartphone. Every machine also includes a lifetime hardware warranty, ensuring immediate replacement support if your unit ever experiences a fault.
Simple Setup with Personal Support
Getting your checkout live shouldn't involve weeks of tedious administrative delays. Setup is quick and entirely guided. You can complete your application online in minutes or speak directly with Jamie to fast-track your direct onboarding. Once verified, your pre-configured terminal arrives ready to process customer cards out of the box, complete with merchant account integration and standard next-day payouts to safeguard daily liquidity.
When accepting card payments for the first time UK merchants deserve complete clarity, dependable equipment, and fair processing fees that support steady business growth.
Transform Your Checkout and Protect Your Cash Flow
Moving away from cash is essential to capture modern consumer spending and eliminate friction at your counter. Yet taking card payments shouldn't come at the expense of restrictive equipment leases or multi-day payout delays that freeze your operating liquidity. When accepting card payments for the first time UK business owners deserve clear commercial terms, rapid next-day settlements, and zero monthly hardware rental fees.
A reliable payment partner protects your margins from your very first trade. By securing a transparent 0.85% transaction fee alongside a lifetime hardware warranty, you gain total peace of mind without worrying about technical hitches or unexpected administrative charges.
Take control of your daily cash flow, welcome every customer with confidence, and give your growing enterprise the modern checkout foundation it deserves.
Frequently Asked Questions
How much does it cost to start accepting card payments in the UK?
Upfront costs can be zero if you choose a transparent provider. Shift4 Card Machine supplies the Shift4 OneCard terminal completely free of monthly rental charges. Instead of paying hefty equipment rental or setup charges, you only pay a simple, fixed 0.85% fee per transaction on credit and debit cards. For businesses accepting card payments for the first time UK wide, this removes the fear of high fixed overheads.
Can I accept card payments without a dedicated business bank account?
No, UK payment acquirers and merchant account providers require a dedicated UK commercial bank account in your legal business name or trading style. This is a mandatory requirement under UK anti-money laundering and financial compliance regulations. Standard personal accounts cannot be linked to commercial merchant accounts, as funds must clear through audited commercial pathways before settling into your operating reserves.
What happens if the Wi-Fi connection drops whilst taking a card payment?
Reliable commercial terminals feature automated network failover. The Shift4 OneCard terminal comes equipped with dual-connectivity, pairing Wi-Fi with a pre-activated 4G mobile SIM. If your local broadband drops out during a sale, the device seamlessly switches to cellular roaming data in seconds. Your checkout never stalls, your queues keep moving, and you won't lose a transaction due to unstable local internet.
How quickly do funds from card transactions reach my bank account?
Payout speeds depend on your acquirer, but modern providers deliver standard next-day payouts. While legacy high-street banks routinely hold money for three to five working days, Shift4 clears your card takings into your nominated UK business bank account the following working day. This rapid settlement protects your operating liquidity, ensuring you have cash on hand for supplier invoices and stock replenishment.
Is my business tied into a multi-year contract for card hardware?
Not with the right provider. Legacy leasing companies historically locked merchants into punitive three-to-four-year hire agreements. Modern setups have moved away from equipment leasing entirely. Shift4 eliminates terminal rental fees by supplying the Shift4 OneCard machine with zero hire charges, backed by an inclusive lifetime hardware warranty. You aren't stuck paying lease fees for outdated equipment that should belong to you.
Can my terminal accept foreign credit cards and mobile digital wallets?
Yes. Modern SmartPOS machines process all major card schemes, including Visa, Mastercard, and American Express, alongside digital wallets like Apple Pay and Google Pay. When accepting card payments for the first time UK merchants can also handle foreign cards seamlessly. Smart terminals automatically convert international currencies via dynamic currency conversion, making it effortless to trade with overseas visitors and tourists.
Do I need a separate phone line or broadband connection to run a card machine?
You don't need a dedicated landline. Modern payment devices operate entirely over wireless connections. You can connect directly to your existing shop Wi-Fi or rely on the terminal's built-in 4G SIM card. Because the machine handles all data securely through mobile networks, you can process sales across your shop floor, at outdoor dining tables, or out on mobile jobs without running extra cables.
Frequently Asked Questions
Upfront costs can be zero if you choose a transparent provider. Shift4 Card Machine supplies the Shift4 OneCard terminal completely free of monthly rental charges. Instead of paying hefty equipment rental or setup charges, you only pay a simple, fixed 0.85% fee per transaction on credit and debit cards. For businesses accepting card payments for the first time UK wide, this removes the fear of high fixed overheads.
No, UK payment acquirers and merchant account providers require a dedicated UK commercial bank account in your legal business name or trading style. This is a mandatory requirement under UK anti-money laundering and financial compliance regulations. Standard personal accounts cannot be linked to commercial merchant accounts, as funds must clear through audited commercial pathways before settling into your operating reserves.
Reliable commercial terminals feature automated network failover. The Shift4 OneCard terminal comes equipped with dual-connectivity, pairing Wi-Fi with a pre-activated 4G mobile SIM. If your local broadband drops out during a sale, the device seamlessly switches to cellular roaming data in seconds. Your checkout never stalls, your queues keep moving, and you won't lose a transaction due to unstable local internet.
Payout speeds depend on your acquirer, but modern providers deliver standard next-day payouts. While legacy high-street banks routinely hold money for three to five working days, Shift4 clears your card takings into your nominated UK business bank account the following working day. This rapid settlement protects your operating liquidity, ensuring you have cash on hand for supplier invoices and stock replenishment.
Not with the right provider. Legacy leasing companies historically locked merchants into punitive three-to-four-year hire agreements. Modern setups have moved away from equipment leasing entirely. Shift4 eliminates terminal rental fees by supplying the Shift4 OneCard machine with zero hire charges, backed by an inclusive lifetime hardware warranty. You aren't stuck paying lease fees for outdated equipment that should belong to you.
Yes. Modern SmartPOS machines process all major card schemes, including Visa, Mastercard, and American Express, alongside digital wallets like Apple Pay and Google Pay. When accepting card payments for the first time UK merchants can also handle foreign cards seamlessly. Smart terminals automatically convert international currencies via dynamic currency conversion, making it effortless to trade with overseas visitors and tourists.
You don't need a dedicated landline. Modern payment devices operate entirely over wireless connections. You can connect directly to your existing shop Wi-Fi or rely on the terminal's built-in 4G SIM card. Because the machine handles all data securely through mobile networks, you can process sales across your shop floor, at outdoor dining tables, or out on mobile jobs without running extra cables.
Related articles
Ready for your free machine?
No rental. No catch. Apply in 2 minutes.