Low Cost Card Payment UK: Navigating the 2026 Merchant Landscape
21 September 2026 · 15 min read
A low headline transaction rate means nothing if your monthly statement arrives packed with terminal hire fees, compliance penalties, and authorisation charges. For independent business owners, securing a genuine low cost card payment UK setup in 2026 isn't just about shaving fractions of a percent off each tap. True value comes from eliminating recurring overheads altogether.
We know the frustration. You work hard to build your trade, only to watch sluggish payout cycles tie up your cash flow whilst opaque rental invoices chip away at your daily profits. You shouldn't have to battle confusing contracts or surprise charges just to take money from your customers. In this guide, you will discover how to eliminate monthly equipment fees, secure simple flat-rate transaction pricing, and unlock reliable next-day access to your takings. We break down the actual mechanics of modern card processing and show you how to keep more of what you earn.
Key Takeaways
- Calculate your true total cost of ownership to secure a genuine low cost card payment UK solution that avoids non-cancellable terminal leases.
- Spot and strip out common statement junk fees, from recurring PCI portal charges to quiet per-attempt authorisation penalties.
- Protect your trading cash flow by replacing multi-day settlement delays with reliable next-day payouts as standard.
- Discover how modern alternatives like the Shift4 OneCard Machine combine a flat 0.85% transaction rate with zero monthly equipment rental.
The 2026 Landscape of Low Cost Card Payment in the UK
High-street banks once held a tight grip on merchant services. If you needed to accept card payments, you visited your branch, signed a multi-year equipment lease, and absorbed whatever arbitrary fees appeared on your statement. That era has finished. Agile independent providers have dismantled the old banking model by offering straightforward merchant accounts, transparent billing, and rapid onboarding.
When searching for a genuine low cost card payment UK setup, the goalpost has shifted. "Low cost" no longer means chasing an artificially reduced headline rate that hides costly surprises elsewhere. Instead, smart business owners evaluate the total cost of ownership across a three-year trading cycle. That means assessing hardware hire, statement fees, and settlement speeds alongside card processing fees.
Consumer habits have driven this change. With smartphone wallets and contactless transactions dominating UK retail counters, merchants cannot afford sluggish payment flows or margin-draining overheads. Concurrently, decisive oversight from the Payment Systems Regulator (PSR) has placed scheme costs and processor markups under unprecedented scrutiny, paving the way for simpler, fairer pricing.
Defining "Low Cost" for the Modern Merchant
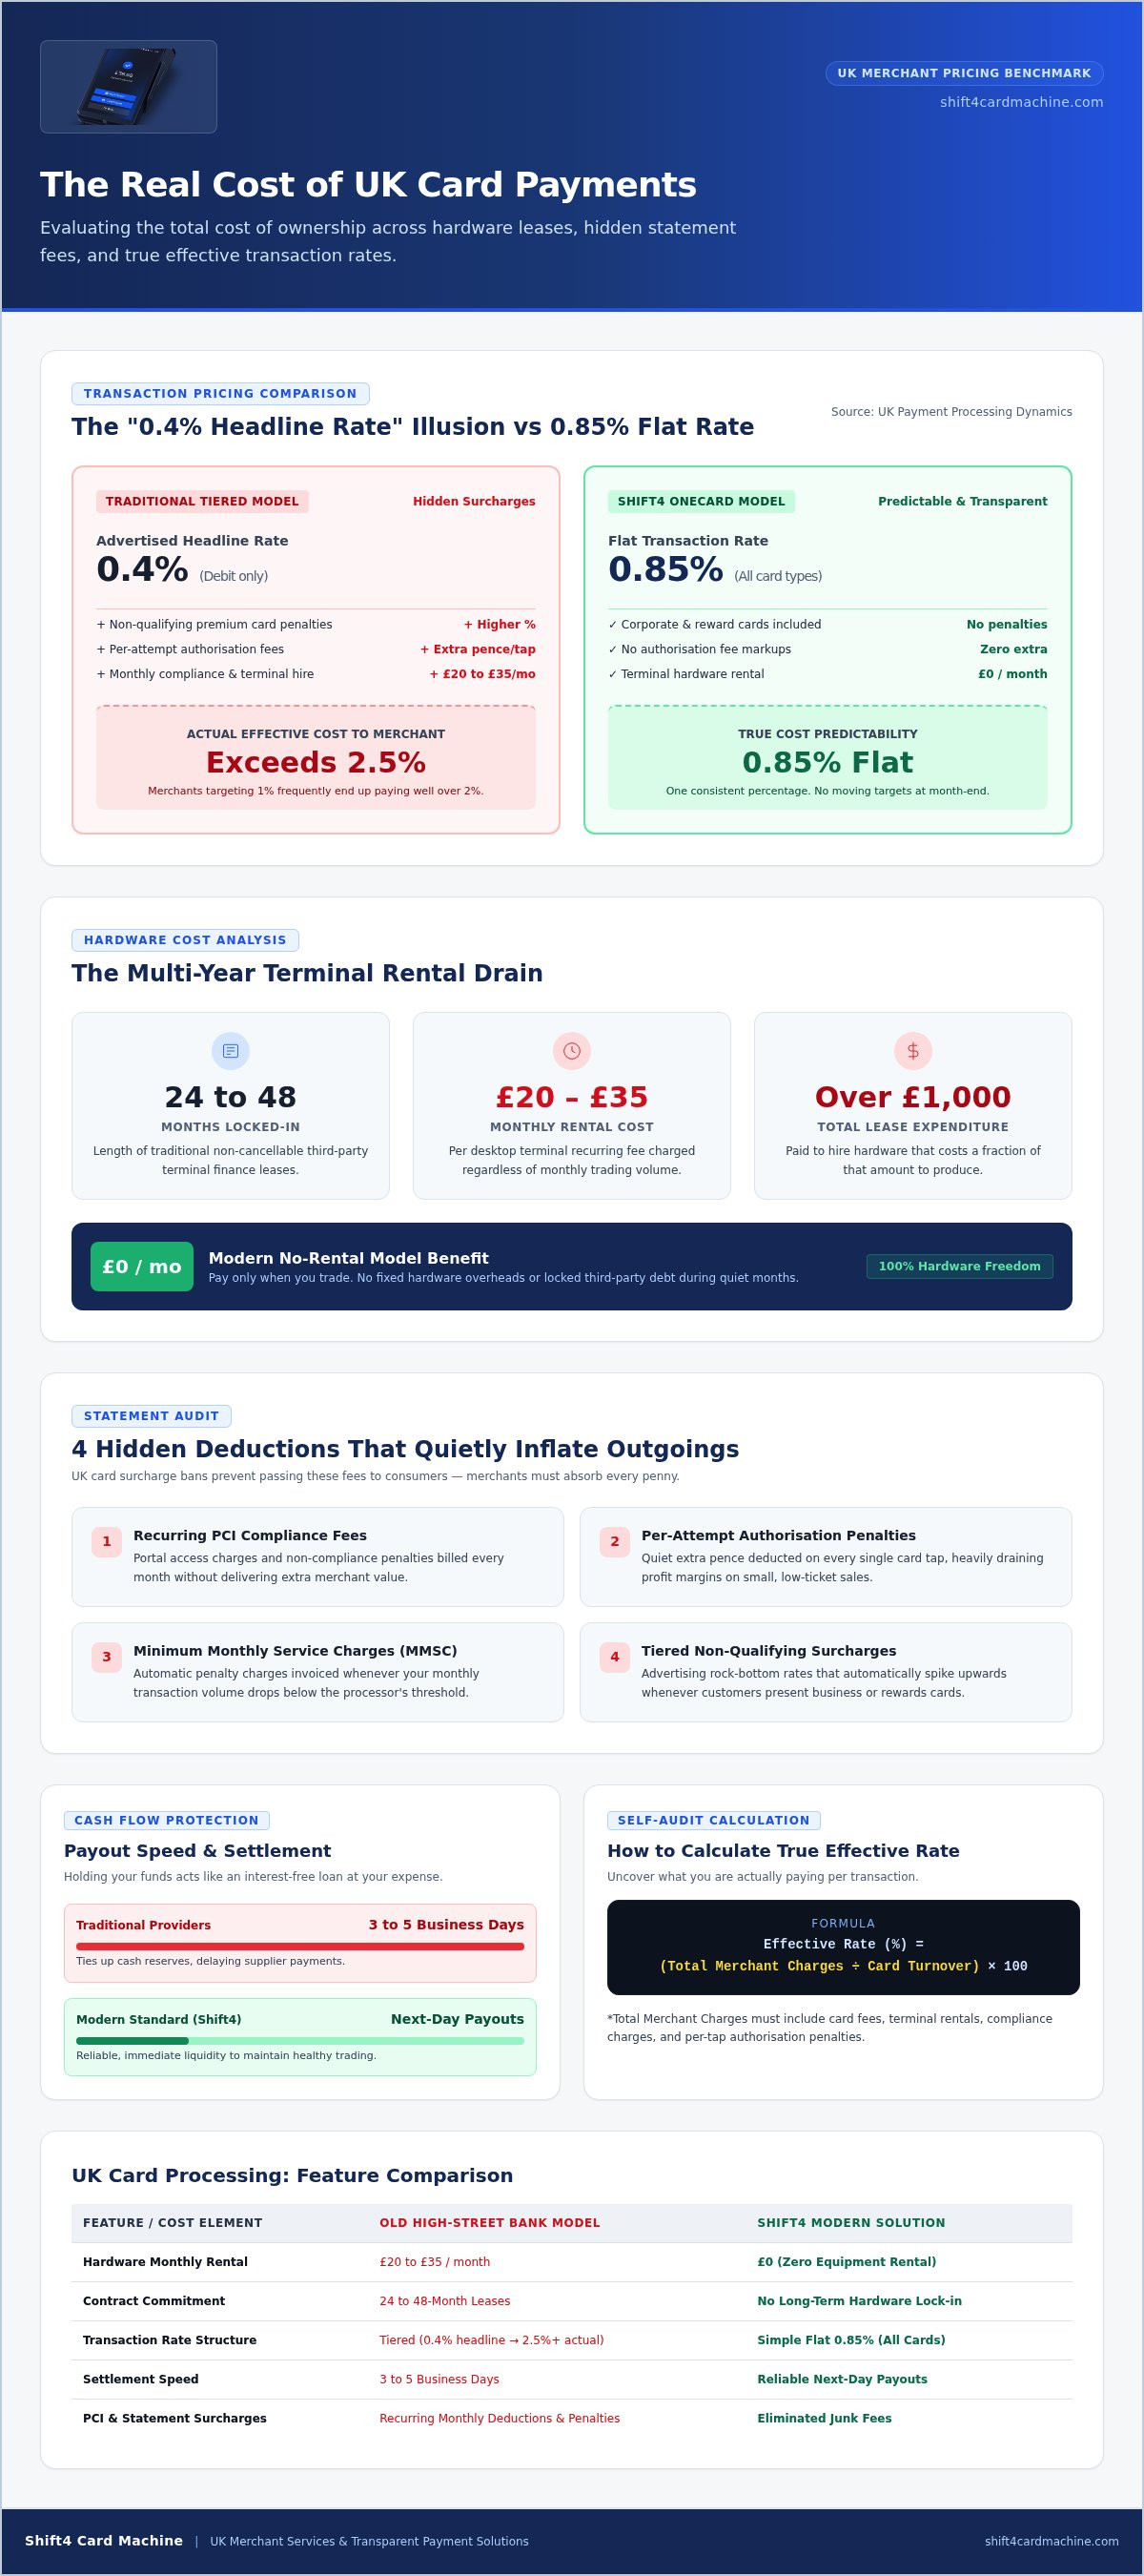
A headline rate of 0.4% sounds unbeatable until your monthly bill arrives. Traditional processors often quote rock-bottom debit rates, only to mask the real expense behind non-qualifying transaction penalties and hidden admin charges. This turns what looked like a bargain into an effective rate that exceeds 2.5%.
While complex pricing structures pass through variable card scheme fees and regulated interchange fees, flat-rate processing models offer welcome clarity. One predictable rate applies across card types. No moving targets. No complicated calculations at month-end. Driven by regulatory pressure and vocal small business advocacy, the UK acquiring sector is leading European peers in championing this fee transparency.
The Death of the Monthly Rental Fee
Terminal leasing has long been one of the biggest drains on merchant profitability. For years, businesses accepted rolling 24 to 48-month hire agreements, paying £20 to £35 every month for a single desktop terminal. Paying over £1,000 to hire hardware that costs a fraction of that to produce makes little financial sense.
Modern cloud architecture has made heavy hardware finance obsolete. Removing monthly rental charges provides instant relief to your bottom line:
- No fixed overheads: You only pay when you trade, keeping quiet months stress-free.
- Aligned incentives: Your provider profits when you succeed, not by locking you into hardware debt.
- Better flexibility: You avoid non-cancellable third-party finance agreements that hold your business hostage.
Deconstructing the Hidden Costs of Payment Processing
A low processing rate looks great on paper. Unfortunately, many merchants soon find that headline numbers tell only half the story. Traditional processing statements are notoriously cluttered with "junk fees" that quietly inflate your outgoings. These extra expenses undermine what was meant to be a low cost card payment UK solution.
Look through an average acquiring invoice, and you will spot recurring deductions that have little to do with actual sales. Monthly PCI compliance fees, portal access charges, minimum monthly service charges (MMSC), and per-transaction authorisation fees chip away at your profits. When an authorisation fee of a few pence is added to every single tap, low-ticket sales take a severe margin hit. Because the UK ban on payment card surcharges prevents retailers from passing these processing expenses onto consumers, your business must absorb every single penny.
The Reality of Transaction Rates
Many providers use tiered pricing that penalises ordinary transactions. They advertise an entry-level debit rate, but the moment a customer pays with a corporate card or a premium rewards card, the transaction is marked as "non-qualifying". The rate shoots up immediately. A clear 0.85% flat rate removes that game completely. You pay one consistent percentage across card types without worrying about unexpected bill spikes at the end of the month.
To find your real baseline, calculate your effective rate: divide your total merchant charges (including all terminal rentals, admin charges, and compliance fees) by your total card turnover, then multiply by 100. Most traders who thought they were on a competitive 1% plan discover they are actually paying well over 2%.
Payout Speed and Business Liquidity
Processing fees are not the only hidden drain on your business. Time costs money too. When an acquirer holds your funds for three to five business days, they are essentially taking an interest-free loan funded by your hard work. Delayed settlements starve your cash reserves, making it harder to settle supplier bills, organise team payroll, or restock essential inventory.
Waiting days for your own takings is completely unnecessary. Modern merchants treat fast settlement as an operational necessity, which is why choosing a card machine next day payout system has become vital for maintaining steady cash flow across all trading sectors. If you are tired of unexpected deductions and sluggish settlements, exploring modern processing alternatives at shift4cardmachine.com offers a practical route to keeping your revenue moving forward without the clutter of legacy bank fees.
Why No-Rental Models are Dominating the UK Market
Locking your business into a multi-year equipment lease is an outdated way to accept payments. Traditional acquirers frequently promote hardware rentals starting from £15 to £30 per month. On the surface, that looks manageable. Over a three-year period, however, you end up handing over hundreds of pounds for a single piece of hardware that is rapidly depreciating. This makes zero commercial sense for an independent trader.
The merchant services sector has evolved. Forward-thinking providers now provide the terminal hardware without recurring rental charges, shifting the commercial focus entirely to transaction processing. This structure creates true alignment between you and your acquirer. The processor earns revenue only when your customers make a purchase. When trading slows down, your overheads drop instantly. That principle forms the cornerstone of genuine low cost card payment UK operations.
The End of Long-Term Lease Commitments
Signing a 36-month terminal lease restricts operational freedom. If your hardware malfunctions, the technology ages, or your trading volume changes, you remain trapped in non-cancellable third-party finance contracts. Many high-street merchants struggle with steep settlement penalties simply trying to exit these agreements early.
Upgrading your checkout setup should never involve financial penalties. When you decide to replace old card machine UK setups, modern zero-rental models let you step into contemporary smart terminals without taking on balance-sheet debt. With solutions like the Shift4 OneCard Machine, you benefit from zero monthly hire costs alongside an ongoing lifetime hardware warranty. If a terminal develops a fault, it gets replaced without extra expense or fresh contractual tie-ins.
Aligning Costs with Revenue
For independent hair salons, cafes, and boutique retailers, footfall varies across the year. Fixed equipment rentals act as an unwelcome tax during post-holiday lulls or bad weather weeks. A pay-as-you-earn structure removes that vulnerability completely.
Here is why this model is now the favourite approach for UK startups and growing enterprises alike:
- Zero dead-weight costs: No sales on a quiet Monday means zero equipment expenses for that day.
- Lower barrier to entry: You can launch, expand counter space, or add extra staff capacity without heavy upfront capital.
- Financial resilience: Your business retains vital working capital, keeping trading margins healthy throughout every season.
How to Audit Your Current Provider for Savings
Taking control of your transaction overhead begins with your monthly processing invoice. Most merchants rarely scrutinise these documents, assuming the figures match their initial sales pitch. In practice, legacy acquirers rely on dense statements and confusing billing codes to quietly inflate your expenses. Securing a true low cost card payment UK solution requires shining a light on these recurring charges.
Start by checking the summary section for unannounced overheads. Look out for monthly statement charges, administrative account fees, or recurring compliance portal deductions. Check your per-transaction authorisation fees as well. These small charges apply to every single tap, whether approved or declined. You should also evaluate your physical hardware. If your terminal relies solely on an ageing Wi-Fi connection and drops transactions during peak lunchtime rushes, you are actively losing trade. Modern setups should feature dual Wi-Fi and roaming 4G connectivity without extra monthly SIM surcharges.
Step-by-Step Statement Analysis
Auditing your statement takes only a few minutes when you follow a methodical process:
- Calculate your real cost: Divide your total monthly fees by your gross card turnover and multiply by 100 to reveal your true effective rate.
- Separate the components: Identify the baseline interchange fees alongside card brand scheme fees, contrasting them directly against your acquirer's added markup.
- Spot regional surcharges: Check whether your provider has applied excessive surcharges to corporate cards or non-EEA consumer transactions.
The Switching Process: Avoiding Exit Fees
Changing your payment setup shouldn't mean facing punitive administrative charges. When preparing to switch card machine provider UK merchants often assume they are completely locked down by legacy paperwork. In reality, switching to a modern provider is straightforward.
Use a clean 0.85% flat rate as your benchmark during contract reviews. If your existing acquirer cannot match that transparency or refuses to waive terminal hire, it is time to move. Setting up seamless merchant account integration takes days rather than weeks, allowing you to transition between providers without missing a single customer sale.
Future-Proofing with Shift4’s Low-Cost Solution
Selecting the right payment provider should simplify your trading life, not complicate it. For modern enterprises seeking a genuine low cost card payment UK partner, the winning strategy requires cutting away financial clutter. No surprise compliance fees. No rolling terminal leases. Shift4 delivers a clear alternative built on operational transparency, giving you complete certainty over payment overheads.
At the heart of this setup is a straightforward 0.85% flat transaction rate. High-volume retail stores, bustling hospitality venues, and independent service providers all share the same requirement: predictable margins. Paying a fixed 0.85% rate across card transactions means your processing costs remain steady regardless of how customers choose to pay. Paired with next-day payouts as standard, your takings land in your bank account promptly, strengthening your daily trading cash flow.
The Shift4 OneCard Advantage
Countertop reliability is non-negotiable during peak trading hours. The Shift4 OneCard Machine features hybrid Wi-Fi and automatic 4G failover, ensuring transactions process instantly even if your broadband cuts out. The device is robust, portable, and ready for all UK retail and hospitality environments.
Unlike high-street banking conglomerates that direct you to overseas call centres, this model connects you directly with a dedicated UK expert. You receive knowledgeable, person-centred support from someone who understands local business challenges. Getting started is equally straightforward. A streamlined online application completes your merchant account integration rapidly, avoiding stacks of complex bank paperwork.
Guaranteeing Long-Term Value
Most card payment providers offer a limited one-year hardware warranty. When their reader fails after 13 months, the merchant pays for a replacement out of pocket. That hidden risk disappears with Shift4. Every terminal includes a lifetime hardware warranty. If your machine encounters a technical fault, it gets swapped out without delay or penalty fees.
Zero monthly equipment rental ensures your business remains resilient through every trading cycle:
- Protected margins: A simple 0.85% flat rate with zero monthly terminal rent.
- Guaranteed hardware: Complete peace of mind through an ongoing lifetime replacement warranty.
- Accelerated cash flow: Automatic next-day settlement directly into your business bank account.
You don't need to accept restrictive contracts or inflated statement fees any longer. Contact Jamie today to claim your free machine and transform your payment processing.
Take Control of Your Payment Processing Margins
Running a thriving business means keeping unnecessary overheads off your balance sheet. By stepping away from multi-year terminal hire contracts and stripping out quiet monthly statement penalties, you take immediate control of your trading margins. Securing an authentic low cost card payment UK setup isn't complicated when you choose total transparency over legacy banking habits.
A clear 0.85% flat transaction rate ensures predictable billing across every customer sale, whilst reliable next-day payouts keep your hard-earned revenue moving directly into your account without delay. Combined with zero monthly rental fees and the lasting protection of an ongoing lifetime hardware warranty, you gain modern point-of-sale reliability without recurring financial drag.
Protect your profits, streamline your daily counter operations, and give your enterprise the fair, transparent foundation it deserves in 2026.
Frequently Asked Questions
What is the average transaction rate for a low cost card payment in the UK?
Typical card processing rates across the UK vary depending on the provider model. Entry-level aggregators often charge between 1.69% and 1.75% per transaction. In contrast, securing an authentic low cost card payment UK solution offers a competitive 0.85% flat rate across standard debit and credit cards. That keeps transaction overheads low and transparent, without masking extra margins behind complex monthly tier systems.
How can I get a card machine with no monthly rental fees?
You can secure a zero-rental terminal by partnering with independent processors that prioritise trading volume over equipment leasing. Shift4 provides the OneCard Machine with zero monthly hire fees. Instead of charging fixed monthly equipment invoices, the provider aligns with your business growth, generating revenue solely from a small percentage per transaction. You simply complete an online application to integrate your merchant account.
Are there any hidden charges in a 0.85% transaction rate?
With a truly transparent merchant partner, a 0.85% flat rate means exactly that. There are no surprise monthly PCI compliance portal charges, no minimum monthly service charges, and no hidden account maintenance fees. You pay a clear percentage on customer sales, with zero equipment rental on your primary terminal. It removes statement confusion, ensuring your end-of-month calculations match your actual turnover.
Can I switch my card machine provider if I am still in a contract?
Yes, switching is entirely possible even if you currently have an existing contract. Start by reviewing your current terms to determine remaining lease commitments or notice periods. For many merchants, eliminating terminal rental fees and dropping to a 0.85% transaction rate generates immediate savings that offset any legacy cancellation charges. You can speak directly with Jamie to map out a seamless transition.
What does a lifetime hardware warranty actually cover?
A lifetime hardware warranty protects your business against terminal breakdowns, internal component faults, and connectivity failures. If your card machine stops working properly during ordinary trading, it is replaced promptly without extra equipment charges. Unlike standard one-year warranties that leave you liable for expensive replacement costs, this ongoing protection ensures your counter operations stay active without unexpected maintenance bills.
How fast can I receive my money with a low-cost merchant account?
Funds are settled into your business bank account the next working day as standard. Older bank arrangements often hold merchant money for three to five business days, creating cash flow bottlenecks. Modern setups ensure your daily card receipts clear promptly, giving you faster access to working capital so you can pay suppliers, manage stock orders, and organise staff payroll with complete confidence.
Is the Shift4 OneCard Machine suitable for high-volume retail environments?
Yes, the Shift4 OneCard Machine is specifically designed to handle high transaction throughput in fast-paced retail stores, restaurants, and salons. Built with rapid contactless processing and automatic hybrid 4G/Wi-Fi switching, it prevents counter delays during busy trading rushes. The sturdy handheld design withstands continuous daily use across diverse UK retail sectors, providing consistent reliability when processing hundreds of taps per day.
Do low-cost card machines support contactless and Apple Pay?
Yes, modern low cost card payment UK terminals fully support contactless payments, Chip and PIN, Apple Pay, and Google Pay. Customers can tap physical cards or use digital mobile wallets with zero checkout friction. Because mobile wallets use biometric authentication directly on smartphones, your checkout counter can handle rapid, secure transactions regardless of whether a purchase sits above standard physical contactless limits.
Frequently Asked Questions
Typical card processing rates across the UK vary depending on the provider model. Entry-level aggregators often charge between 1.69% and 1.75% per transaction. In contrast, securing an authentic low cost card payment UK solution offers a competitive 0.85% flat rate across standard debit and credit cards. That keeps transaction overheads low and transparent, without masking extra margins behind complex monthly tier systems.
You can secure a zero-rental terminal by partnering with independent processors that prioritise trading volume over equipment leasing. Shift4 provides the OneCard Machine with zero monthly hire fees. Instead of charging fixed monthly equipment invoices, the provider aligns with your business growth, generating revenue solely from a small percentage per transaction. You simply complete an online application to integrate your merchant account.
With a truly transparent merchant partner, a 0.85% flat rate means exactly that. There are no surprise monthly PCI compliance portal charges, no minimum monthly service charges, and no hidden account maintenance fees. You pay a clear percentage on customer sales, with zero equipment rental on your primary terminal. It removes statement confusion, ensuring your end-of-month calculations match your actual turnover.
Yes, switching is entirely possible even if you currently have an existing contract. Start by reviewing your current terms to determine remaining lease commitments or notice periods. For many merchants, eliminating terminal rental fees and dropping to a 0.85% transaction rate generates immediate savings that offset any legacy cancellation charges. You can speak directly with Jamie to map out a seamless transition.
A lifetime hardware warranty protects your business against terminal breakdowns, internal component faults, and connectivity failures. If your card machine stops working properly during ordinary trading, it is replaced promptly without extra equipment charges. Unlike standard one-year warranties that leave you liable for expensive replacement costs, this ongoing protection ensures your counter operations stay active without unexpected maintenance bills.
Funds are settled into your business bank account the next working day as standard. Older bank arrangements often hold merchant money for three to five business days, creating cash flow bottlenecks. Modern setups ensure your daily card receipts clear promptly, giving you faster access to working capital so you can pay suppliers, manage stock orders, and organise staff payroll with complete confidence.
Yes, the Shift4 OneCard Machine is specifically designed to handle high transaction throughput in fast-paced retail stores, restaurants, and salons. Built with rapid contactless processing and automatic hybrid 4G/Wi-Fi switching, it prevents counter delays during busy trading rushes. The sturdy handheld design withstands continuous daily use across diverse UK retail sectors, providing consistent reliability when processing hundreds of taps per day.
Yes, modern low cost card payment UK terminals fully support contactless payments, Chip and PIN, Apple Pay, and Google Pay. Customers can tap physical cards or use digital mobile wallets with zero checkout friction. Because mobile wallets use biometric authentication directly on smartphones, your checkout counter can handle rapid, secure transactions regardless of whether a purchase sits above standard physical contactless limits.
Related articles
Ready for your free machine?
No rental. No catch. Apply in 2 minutes.