How to Switch Card Machine Provider UK: 2026 Guide
18 September 2026 · 18 min read
Why are you still paying a monthly fee to rent a piece of plastic that actually slows down your business? If you’ve noticed "PCI compliance" or "admin" charges creeping onto your statements, you aren't alone. It is frustrating to watch hard-earned profits vanish into hidden fees whilst waiting three business days for your own money to clear. You want lower rates and faster access to your cash. You want a provider that acts like a partner, not a tax collector.
Mastering how to switch card machine provider UK is the fastest way to reclaim your margins in 2026. This guide simplifies the entire process. We will show you how to navigate the latest PSR regulations to avoid exit fees and secure transaction rates well below 1%. No more rental traps. No more "T+3" settlement delays. We are breaking down the five-step transition to next-day payouts and modern, lifetime-guaranteed hardware that costs you nothing every month. It is time to stop settling for legacy contracts and start prioritising your business cash flow.
Key Takeaways
- Master the 5-step transition on how to switch card machine provider UK to stop overpaying for legacy hardware and hidden fees.
- Leverage current PSR regulations to bypass excessive exit fees and move to a flexible, rolling 30-day notice period.
- Secure a transparent 0.85% flat transaction rate and eliminate unpredictable monthly costs like PCI or admin charges.
- Boost your business liquidity by moving from slow three-day settlement cycles to guaranteed next-day payouts.
- End the hardware rental cycle forever with a lifetime warranty and zero monthly terminal hire costs.
Why UK Merchants are Switching Card Machine Providers in 2026
The UK payment market is undergoing its biggest shake-up in a decade. New regulations from the Payment Systems Regulator (PSR) have finally capped terminal leases at 18 months for most small businesses. This shift has exposed the flaws in the old way of doing things. For too long, merchants were locked into 36 or 48-month cycles, paying for hardware that became obsolete long before the contract ended. Today, the trend is clear. Merchants want flexibility, fairness, and a partner that actually supports their growth.
The rapid evolution of payment terminal technology has completely changed expectations. Modern devices now combine 4G and Wi-Fi as standard, ensuring you never miss a sale due to a dropped connection or a broadband failure. If your current provider still charges you for a basic countertop unit whilst holding your funds for three business days, you have reached the tipping point. Learning how to switch card machine provider UK is no longer just a cost-saving exercise; it is a strategic move to regain control of your revenue and your time.
The Hidden Costs of Legacy Contracts
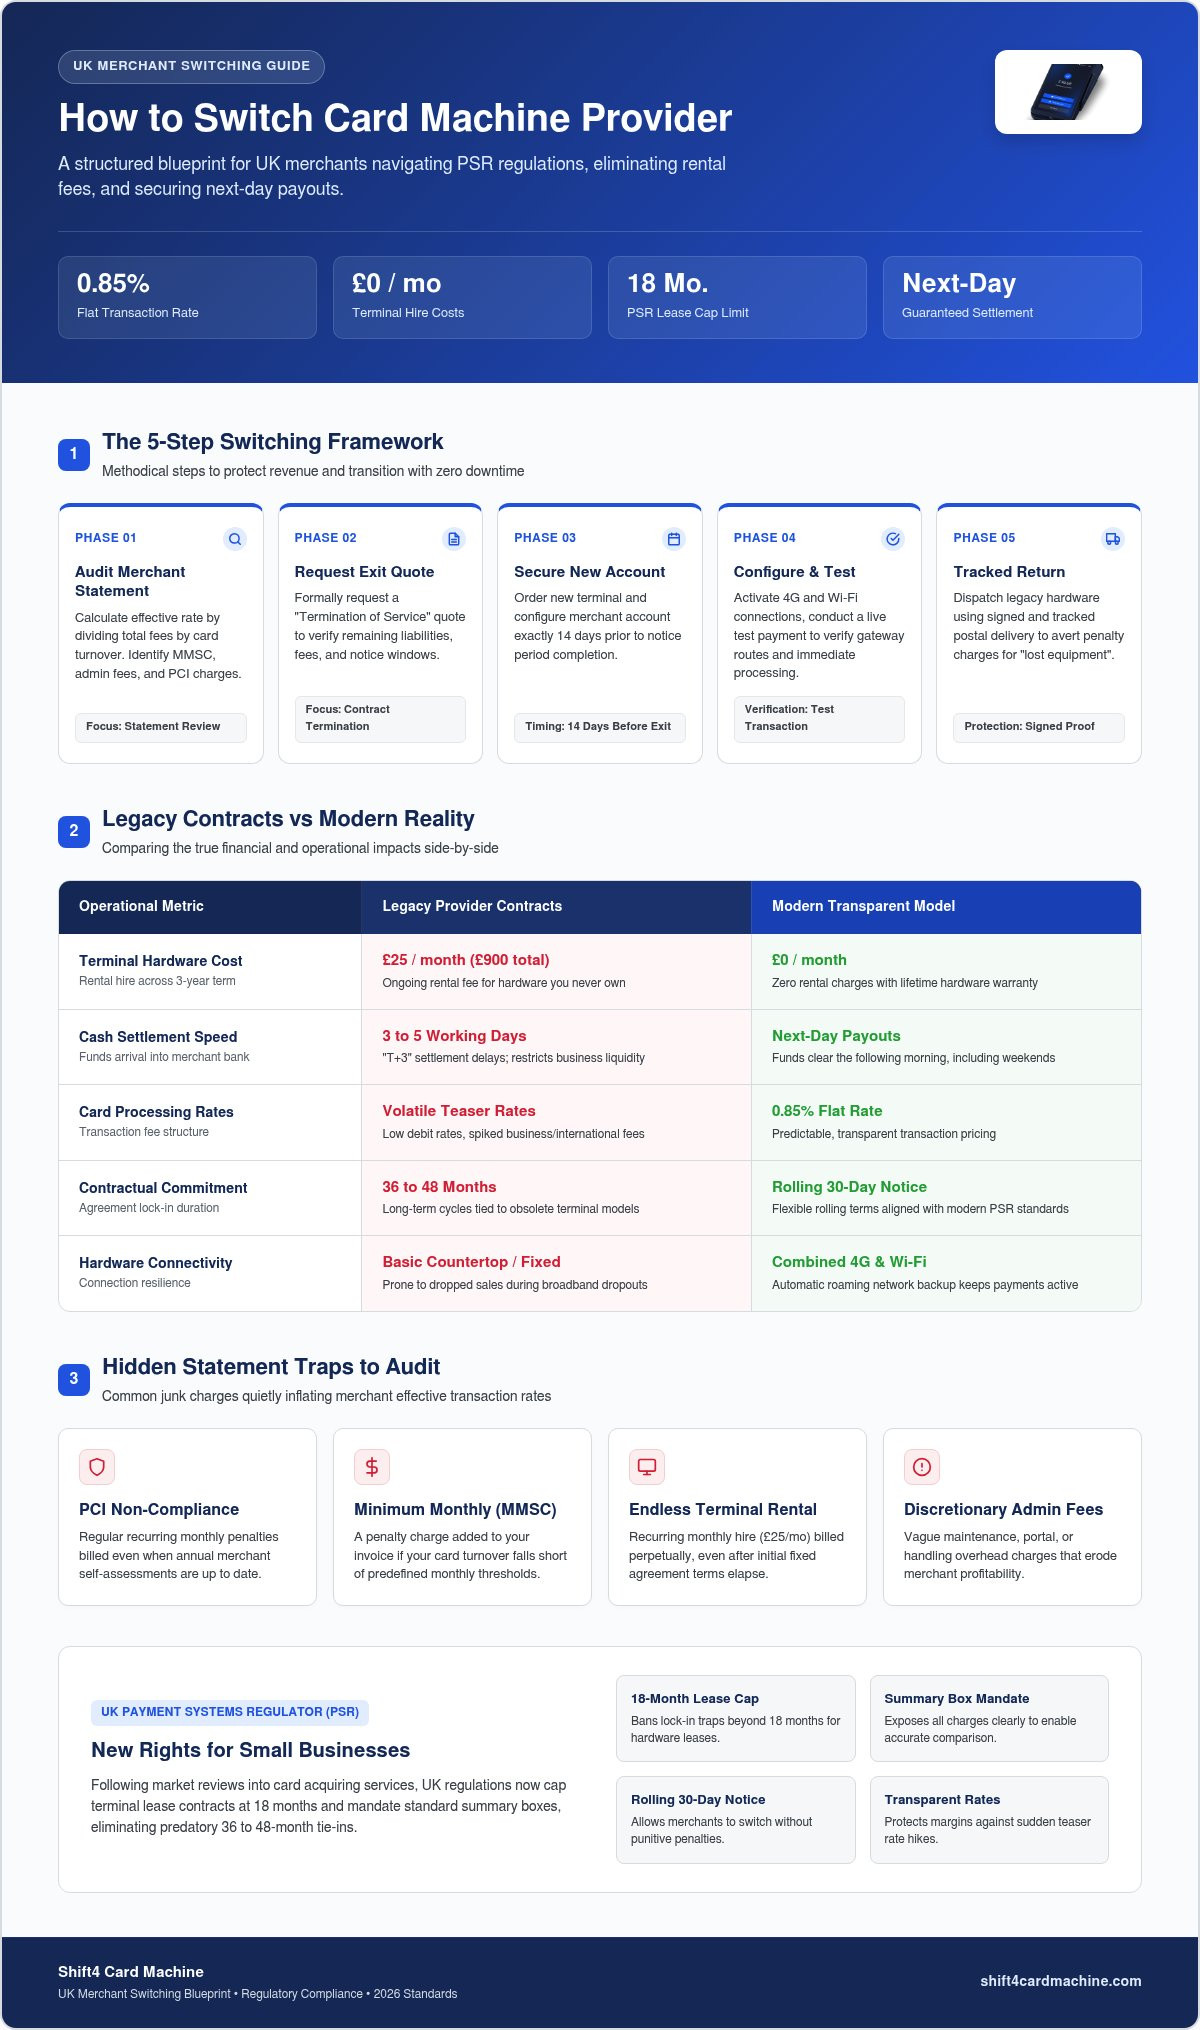
Many older contracts are riddled with "junk fees" that only appear after the initial honeymoon period ends. You might see monthly PCI non-compliance fees even after you have completed your self-assessment. Admin charges and Minimum Monthly Service Charges (MMSC) can quietly inflate your effective rate without you noticing. Teaser rates are another common trap. A provider might offer a low headline rate for consumer debit cards, only to squeeze your margins with much higher fees for business, corporate, or international cards. These costs add up significantly. A merchant paying £25 a month for a basic terminal rental spends £900 over three years for hardware they will never own. This outdated model is exactly why so many are researching how to switch card machine provider UK to find a more transparent alternative.
Modern Expectations for Payment Speed
Cash flow is the lifeblood of any retail or hospitality business. Waiting three to five working days for your money to clear is a relic of the past that hurts your ability to restock or pay staff. Next-day payouts are now the industry benchmark. When you optimise business cash flow with faster settlements, you gain the agility to respond to market demands instantly. Faster access to your funds means better stock management and less reliance on expensive overdrafts or short-term loans. Moving to a provider that settles your funds the next morning, including weekends, ensures your bank balance always reflects your actual sales. It is about creating a seamless bridge between your hard work and your liquidity.
How to Switch Card Machine Provider: The 5-Step Process
Switching is simpler than legacy providers want you to think. It is a structured journey that, when followed correctly, protects your revenue and removes the stress of technical downtime. By following these five steps, you can move from an expensive, restrictive contract to a modern solution that prioritises your cash flow.
- Step 1: Audit your current merchant statement for hidden fees and "junk" charges.
- Step 2: Request a formal "Termination of Service" quote to confirm your exit costs.
- Step 3: Secure your new hardware and merchant account 14 days before your notice period ends.
- Step 4: Configure your new terminal and perform a test transaction to verify the connection.
- Step 5: Return your old equipment via tracked delivery to prevent "lost hardware" penalties.
Step 1: Auditing Your Current Statement
Start by calculating your "Effective Rate" to see what you are actually paying. Take the total fees charged on your last statement and divide them by your total card turnover. This figure is often significantly higher than the headline rate you were originally promised. Look closely for the Minimum Monthly Service Charge (MMSC). This is a penalty fee applied if your transaction volume falls below a certain threshold. You should also check for terminal rental fees that might still be active even if your initial contract term has expired. The Payment Systems Regulator market review addressed these transparency issues, leading to new requirements for summary boxes that make these costs easier to spot. If your statement is cluttered with PCI non-compliance fees despite you being compliant, it is a clear sign to move on.
Step 2 & 3: Managing the Transition
Once you have identified the leaks in your current setup, request a termination quote. This document is essential because it puts your provider on notice and forces them to disclose any final exit fees. Don't leave this until the final week. We recommend applying for your merchant services UK no monthly fee solution at least two weeks before your current notice period expires. This overlap creates a safety net. It allows you to receive and test your new hardware whilst your old service is still active, ensuring zero downtime for your customers. If you are worried about the cost of leaving, you can explore switching to a free terminal model to immediately offset any remaining legacy contract fees. This proactive approach ensures a seamless handover that keeps your business trading without interruption.
The final hurdle is the physical return of your old machine. Always use a tracked courier service and retain the proof of postage. Many legacy providers are known for issuing "lost equipment" invoices months after a switch. A tracking number is your only definitive proof that the hardware was returned, saving you from one last unexpected bill.
Navigating Exit Fees and Contract Notice Periods
Fear of a final bill shouldn't keep you trapped in an uncompetitive contract. Many legacy providers rely on inertia and the threat of exit fees to prevent you from looking elsewhere. However, the landscape has changed. The standard notice period in the UK is now 30 days once your initial term concludes. If you have been with your provider for over 18 months, you are likely on a rolling monthly agreement. This makes knowing how to switch card machine provider UK a matter of simple timing rather than a legal battle.
Don't let the phrase "automatic renewal" intimidate you. Current UK regulations have significantly weakened the ability of providers to lock small businesses into long-term extensions without explicit consent. Moving to a "no contract" or flexible model is the best way to future-proof your business. It ensures that you stay because the service is excellent, not because a legal clause is holding you hostage. It is about reclaiming your right to choose what is best for your bottom line.
Challenging Unfair Terms
Don't accept a sudden rate hike as inevitable. If your provider increases their fees, they must give you at least 30 days’ written notice. This is known as a "Notice of Variation". In many cases, this change gives you a legal window to exit your contract for free, even if you are still in your initial term. If a provider refuses to honour this or tries to enforce an automatic renewal that feels predatory, the Financial Ombudsman is there to help. They handle merchant service disputes with a focus on fairness, often siding with small businesses that have been misled by complex small print or hidden charges. Being proactive with your current provider often reveals that those "fixed" exit fees are more negotiable than they first appear.
The ROI of Switching
Calculate your return on investment before you sign anything. If you are currently on a 1.75% flat rate and process £20,000 a month, you are paying £350 in fees. Switching to a 0.85% rate drops that to £170. That is a saving of £180 every single month. Even if your current provider demands a £150 exit fee, you have cleared that cost in less than four weeks. When you factor in the statutory caps on interchange fees, which limit the underlying costs to 0.2% for debit and 0.3% for credit, it becomes clear how much margin legacy providers are keeping for themselves. Choosing the best card machine isn't just about the hardware; it's about ending the £20-per-month rental cycle and moving to a model that respects your business's future. Remember to factor in the value of next-day payouts. Faster access to your cash means less reliance on expensive overdrafts, adding even more to your total savings.
Comparing Transaction Rates: What is a "Good Deal" in 2026?
When you start researching how to switch card machine provider UK, the first number you likely look for is the transaction rate. It is the most visible cost, but it is often the most misunderstood. Many providers use "blended" rates to simplify things, whilst others use Interchange Plus Plus (IC++) to show every individual cost layer. For a growing business, the goal is transparency. You need to know that the rate you are quoted is the rate you will actually pay, regardless of whether your customer uses a standard debit card or a rewards-heavy credit card.
Be wary of the "0% transaction fee" marketing trap. These offers often hide high monthly membership fees that can exceed £100. Unless you are processing huge volumes, these fixed costs usually work out more expensive than a standard percentage. A truly good deal provides a low, predictable rate without the burden of heavy monthly subscriptions. You should also ensure your quoted rate applies to both debit and credit cards equally to avoid nasty surprises on your end-of-month statement.
Flat Rates vs. Complex Tiered Pricing
Legacy providers often use tiered pricing models, categorising transactions as "Qualified," "Mid-Qualified," or "Non-Qualified." This system is designed to be confusing. It allows providers to quote a low "Qualified" rate that rarely applies to the cards your customers actually use. A flat rate removes this guesswork entirely. A flat 0.85% transaction rate represents the gold standard for competitive UK processing in 2026, offering a perfect balance of affordability and simplicity. It means you know exactly what every pound of sales costs you, allowing for much more accurate financial planning and better protection of your margins.
Beyond the Rate: Hardware and Support
A cheap rate becomes an expensive mistake if your terminal fails during a busy Saturday night service. Reliability is just as important as the percentage on your statement. When looking at how to switch card machine provider UK, prioritise providers that offer a lifetime hardware warranty. This protects you from unexpected replacement costs and ensures you always have the latest payment terminal technology at your fingertips. Local, UK-based support is also vital. You don't want to be stuck in a global call centre queue when you have a queue of customers waiting to pay. Speed of resolution is a key part of the value you are buying, ensuring your business never misses a beat.
Making the Switch to Shift4 OneCard Machine
You have seen the data. You know the steps. Now, it is time to choose the partner that ends the cycle of hidden fees and slow payouts. Mastering how to switch card machine provider UK becomes effortless when you move to a platform designed for merchant success. The Shift4 Card Machine isn't just another terminal. It is a complete shift in how you handle payments. No more monthly rental. No more complex statements. Just a straightforward 0.85% flat rate that lets you keep more of what you earn.
By choosing this path, you are removing the friction that legacy banks rely on to keep you trapped. We don't just offer a different rate; we offer a different relationship. One built on transparency, speed, and reliability. It is about making this the last switch your business ever needs to make.
The Shift4 Card Machine Advantage
The Shift4 Card Machine is engineered to remove every common merchant pain point. Most providers charge you £20 to £30 a month just to have a machine on your counter. We don't. We provide the hardware for free. This instantly nullifies the "exit fee" objection from your old provider. If you save £300 a year on rental alone, the switch pays for itself before you even process your first transaction.
Reliability is built-in. The terminal features a hybrid 4G and Wi-Fi connection. If your shop's broadband goes down, the 4G SIM kicks in automatically. You never miss a sale. We back this with a lifetime hardware warranty. If it breaks, we replace it. It is that simple. Combine this with next-day payouts as standard, and your cash flow becomes faster and more predictable. No more waiting for "T+3" cycles. Your money arrives when you need it.
Getting Started Today
Ready to reclaim your margins? The application process is fast and entirely online. You don't need to navigate a corporate maze. To make the move, you'll generally need your business bank details, proof of ID, and a recent merchant statement. This helps us verify your turnover and set up your 0.85% programme immediately. We handle the merchant account integration so you can focus on running your business.
We believe in a human connection. You aren't just another account number to us. If you have specific questions about how to switch card machine provider UK for your unique business model, you can contact Jamie directly. He provides personalised switching consultations to ensure your transition is smooth, fast, and profitable. It is time to stop paying for the past and start investing in your business's future. Join the thousands of UK merchants who have already ended the rental trap.
Take Control of Your Business Cash Flow
You now have a clear, actionable roadmap for how to switch card machine provider UK without the traditional headaches. By auditing your current statements and understanding your rights under current PSR regulations, you can finally break free from restrictive legacy contracts. It is about moving away from unpredictable "junk" fees and embracing a model where you actually own your margins. This transition isn't just a technical change; it is a strategic move to protect your hard-earned revenue.
Moving to next-day payouts as standard and zero monthly rental fees is the most impactful change you can make for your business liquidity this year. You deserve hardware that works as hard as you do, supported by a lifetime hardware warranty that ensures you never miss a sale. This is your opportunity to simplify your operations and reclaim the profit that legacy providers have been siphoning off through hidden admin charges and slow settlement cycles.
Your business deserves a payment partner that prioritises transparency over complex fine print. Take the first step toward a more profitable and predictable future today. We are ready to help you make the last switch you will ever need to make.
Frequently Asked Questions
How long does it typically take to switch card machine providers in the UK?
Switching typically takes between three and five working days from your initial application to receiving your new hardware. Once you provide your business details and recent statements, the underwriting process moves quickly. We aim to get your pre-configured Shift4 OneCard Machine delivered to you as fast as possible. If you need a faster turnaround, you can contact Jamie directly for a personalised consultation. This ensures you can transition smoothly without missing a single day of trading.
Will I have to pay an exit fee to my current provider?
Whether you pay an exit fee depends on your current contract stage and the length of your initial term. Under PSR regulations, most small business terminal leases are now capped at 18 months. If you are outside this window, you likely only owe a 30-day notice period. Many merchants find that switching to a £0 rental model with 0.85% rates covers the cost of any exit fees within the first month.
Can I keep my existing merchant account when I switch machines?
You generally cannot keep your old merchant account when moving to a more modern, integrated solution. We provide full merchant account integration as part of our service to ensure you benefit from our 0.85% flat rates and next-day payouts. This all-in-one approach removes the friction of dealing with multiple providers. It also ensures that your hardware and payment processing work together perfectly with a single point of contact for any technical support you might need.
What is the difference between a merchant account and a card machine provider?
A merchant account is a specific type of bank account that allows your business to accept card payments and hold funds before they are settled. The card machine provider supplies the physical hardware and the software used to process the transaction. Whilst legacy banks often separate these services, we integrate them. This means you get your Shift4 OneCard Machine and your processing account in one streamlined package, making it much easier to manage your finances.
Is it possible to switch providers if I am mid-way through a long-term contract?
It is entirely possible to switch providers even if you are mid-contract. You should first request a termination quote to see the exact cost of leaving early. For many UK businesses, the savings from eliminating monthly rental fees and high transaction rates outweigh the one-off cost of an exit fee. We help you calculate this ROI so you can decide if moving to a more transparent provider makes financial sense for your business right now.
How do I avoid downtime during the switching process?
Avoiding downtime is simple if you overlap your new and old services by about 14 days. Apply for your new solution whilst your old contract is still active. Once your Shift4 OneCard Machine arrives, perform a test transaction to ensure everything is connected. Only after you are successfully processing payments on the new hardware should you return your old equipment. This proactive approach ensures your customers can always pay without any technical interruptions or lost revenue.
Are there any card machines with no monthly fees or contracts in the UK?
Yes, there are now options for card machines with no monthly rental fees or long-term restrictive contracts. We provide the Shift4 OneCard Machine for free, removing the rental trap that many legacy providers use to inflate their margins. You only pay the 0.85% transaction fee on the sales you actually make. This flexible model is designed to support your growth rather than burdening your business with fixed costs during quieter trading periods.
What happens to my old card machine after I switch?
When you learn how to switch card machine provider UK, you must remember that old leased equipment remains the property of the original provider. You must return the hardware via a tracked courier service once your notice period ends. Always keep your proof of postage. This prevents the old provider from charging you lost equipment fees, which can be several hundred pounds. It is the final step in successfully closing your old account and moving forward.
Frequently Asked Questions
Switching typically takes between three and five working days from your initial application to receiving your new hardware. Once you provide your business details and recent statements, the underwriting process moves quickly. We aim to get your pre-configured Shift4 OneCard Machine delivered to you as fast as possible. If you need a faster turnaround, you can contact Jamie directly for a personalised consultation. This ensures you can transition smoothly without missing a single day of trading.
Whether you pay an exit fee depends on your current contract stage and the length of your initial term. Under PSR regulations, most small business terminal leases are now capped at 18 months. If you are outside this window, you likely only owe a 30-day notice period. Many merchants find that switching to a £0 rental model with 0.85% rates covers the cost of any exit fees within the first month.
You generally cannot keep your old merchant account when moving to a more modern, integrated solution. We provide full merchant account integration as part of our service to ensure you benefit from our 0.85% flat rates and next-day payouts. This all-in-one approach removes the friction of dealing with multiple providers. It also ensures that your hardware and payment processing work together perfectly with a single point of contact for any technical support you might need.
A merchant account is a specific type of bank account that allows your business to accept card payments and hold funds before they are settled. The card machine provider supplies the physical hardware and the software used to process the transaction. Whilst legacy banks often separate these services, we integrate them. This means you get your Shift4 OneCard Machine and your processing account in one streamlined package, making it much easier to manage your finances.
It is entirely possible to switch providers even if you are mid-contract. You should first request a termination quote to see the exact cost of leaving early. For many UK businesses, the savings from eliminating monthly rental fees and high transaction rates outweigh the one-off cost of an exit fee. We help you calculate this ROI so you can decide if moving to a more transparent provider makes financial sense for your business right now.
Avoiding downtime is simple if you overlap your new and old services by about 14 days. Apply for your new solution whilst your old contract is still active. Once your Shift4 OneCard Machine arrives, perform a test transaction to ensure everything is connected. Only after you are successfully processing payments on the new hardware should you return your old equipment. This proactive approach ensures your customers can always pay without any technical interruptions or lost revenue.
Yes, there are now options for card machines with no monthly rental fees or long-term restrictive contracts. We provide the Shift4 OneCard Machine for free, removing the rental trap that many legacy providers use to inflate their margins. You only pay the 0.85% transaction fee on the sales you actually make. This flexible model is designed to support your growth rather than burdening your business with fixed costs during quieter trading periods.
When you learn how to switch card machine provider UK, you must remember that old leased equipment remains the property of the original provider. You must return the hardware via a tracked courier service once your notice period ends. Always keep your proof of postage. This prevents the old provider from charging you lost equipment fees, which can be several hundred pounds. It is the final step in successfully closing your old account and moving forward.
Related articles
Ready for your free machine?
No rental. No catch. Apply in 2 minutes.