Understanding Card Processing Fees UK: The 2026 Merchant Guide
17 September 2026 · 16 min read
Why does your "low" transaction rate always look so much higher once your monthly statement actually arrives? You aren't imagining the discrepancy. Most UK business owners are currently trapped in a cycle of hidden PCI compliance charges, opaque "non-qualified" surcharges, and frustrating payout delays. It's time for a more transparent approach to understanding card processing fees UK. We agree that you should spend your time growing your business, not decoding a financial riddle wrapped in jargon.
You're about to master the complexities of the payments industry and learn how to eliminate the hidden costs draining your accounts. This guide promises to demystify the difference between Interchange and Scheme fees; it also highlights why monthly rental overheads are an unnecessary burden. We'll explore a simpler, more predictable way to manage your money with a fixed 0.85% rate and next-day payouts. No more hidden extras. No more rental fees. Just a reliable Shift4 OneCard Machine and the clarity your business deserves.
Key Takeaways
- Master the basics of understanding card processing fees UK to reclaim control over your business finances and stop overpaying.
- Identify and eliminate hidden "gotchas" such as PCI compliance penalties and minimum monthly service charges that drain your profits.
- Decode the "three pillars" of fees—Interchange, Scheme, and Acquirer—to see exactly where every penny of your transaction goes.
- Say goodbye to monthly rental overheads by switching to a simple, transparent 0.85% fixed transaction rate.
- Boost your daily cash flow with next-day payouts as standard, removing the anxiety and friction of long processing delays.
Decoding the UK Card Processing Fee Landscape in 2026
Think of merchant services as the vital bridge between your customer's bank and your business account. It's the invisible infrastructure that turns a digital tap into usable capital. Whilst the volume of digital payments has skyrocketed, the underlying fee structures have become increasingly layered. Mastering the art of understanding card processing fees UK is now a requirement for survival. It's a shift from seeing fees as an unavoidable cost to managing them as a strategic part of your cash flow. You need to know exactly where your money goes before it reaches your balance. The Merchant Service Charge is the total percentage paid per transaction.
The Evolution of UK Payment Regulation
Post-Brexit adjustments have significantly influenced how major card brands manage their internal costs amongst UK merchants. These changes often impact interchange fees and scheme charges, creating a ripple effect on your monthly statement. The Payment Systems Regulator (PSR) acts as a watchdog here. They aim to ensure small businesses aren't unfairly penalised by dominant market players. In 2026, the trend is clear. Contactless and mobile wallet payments are no longer optional extras; they are the primary way the UK shops. Your processing setup must be fast, reliable, and transparent to keep pace with these evolving consumer habits.
Why One Rate Rarely Means One Price
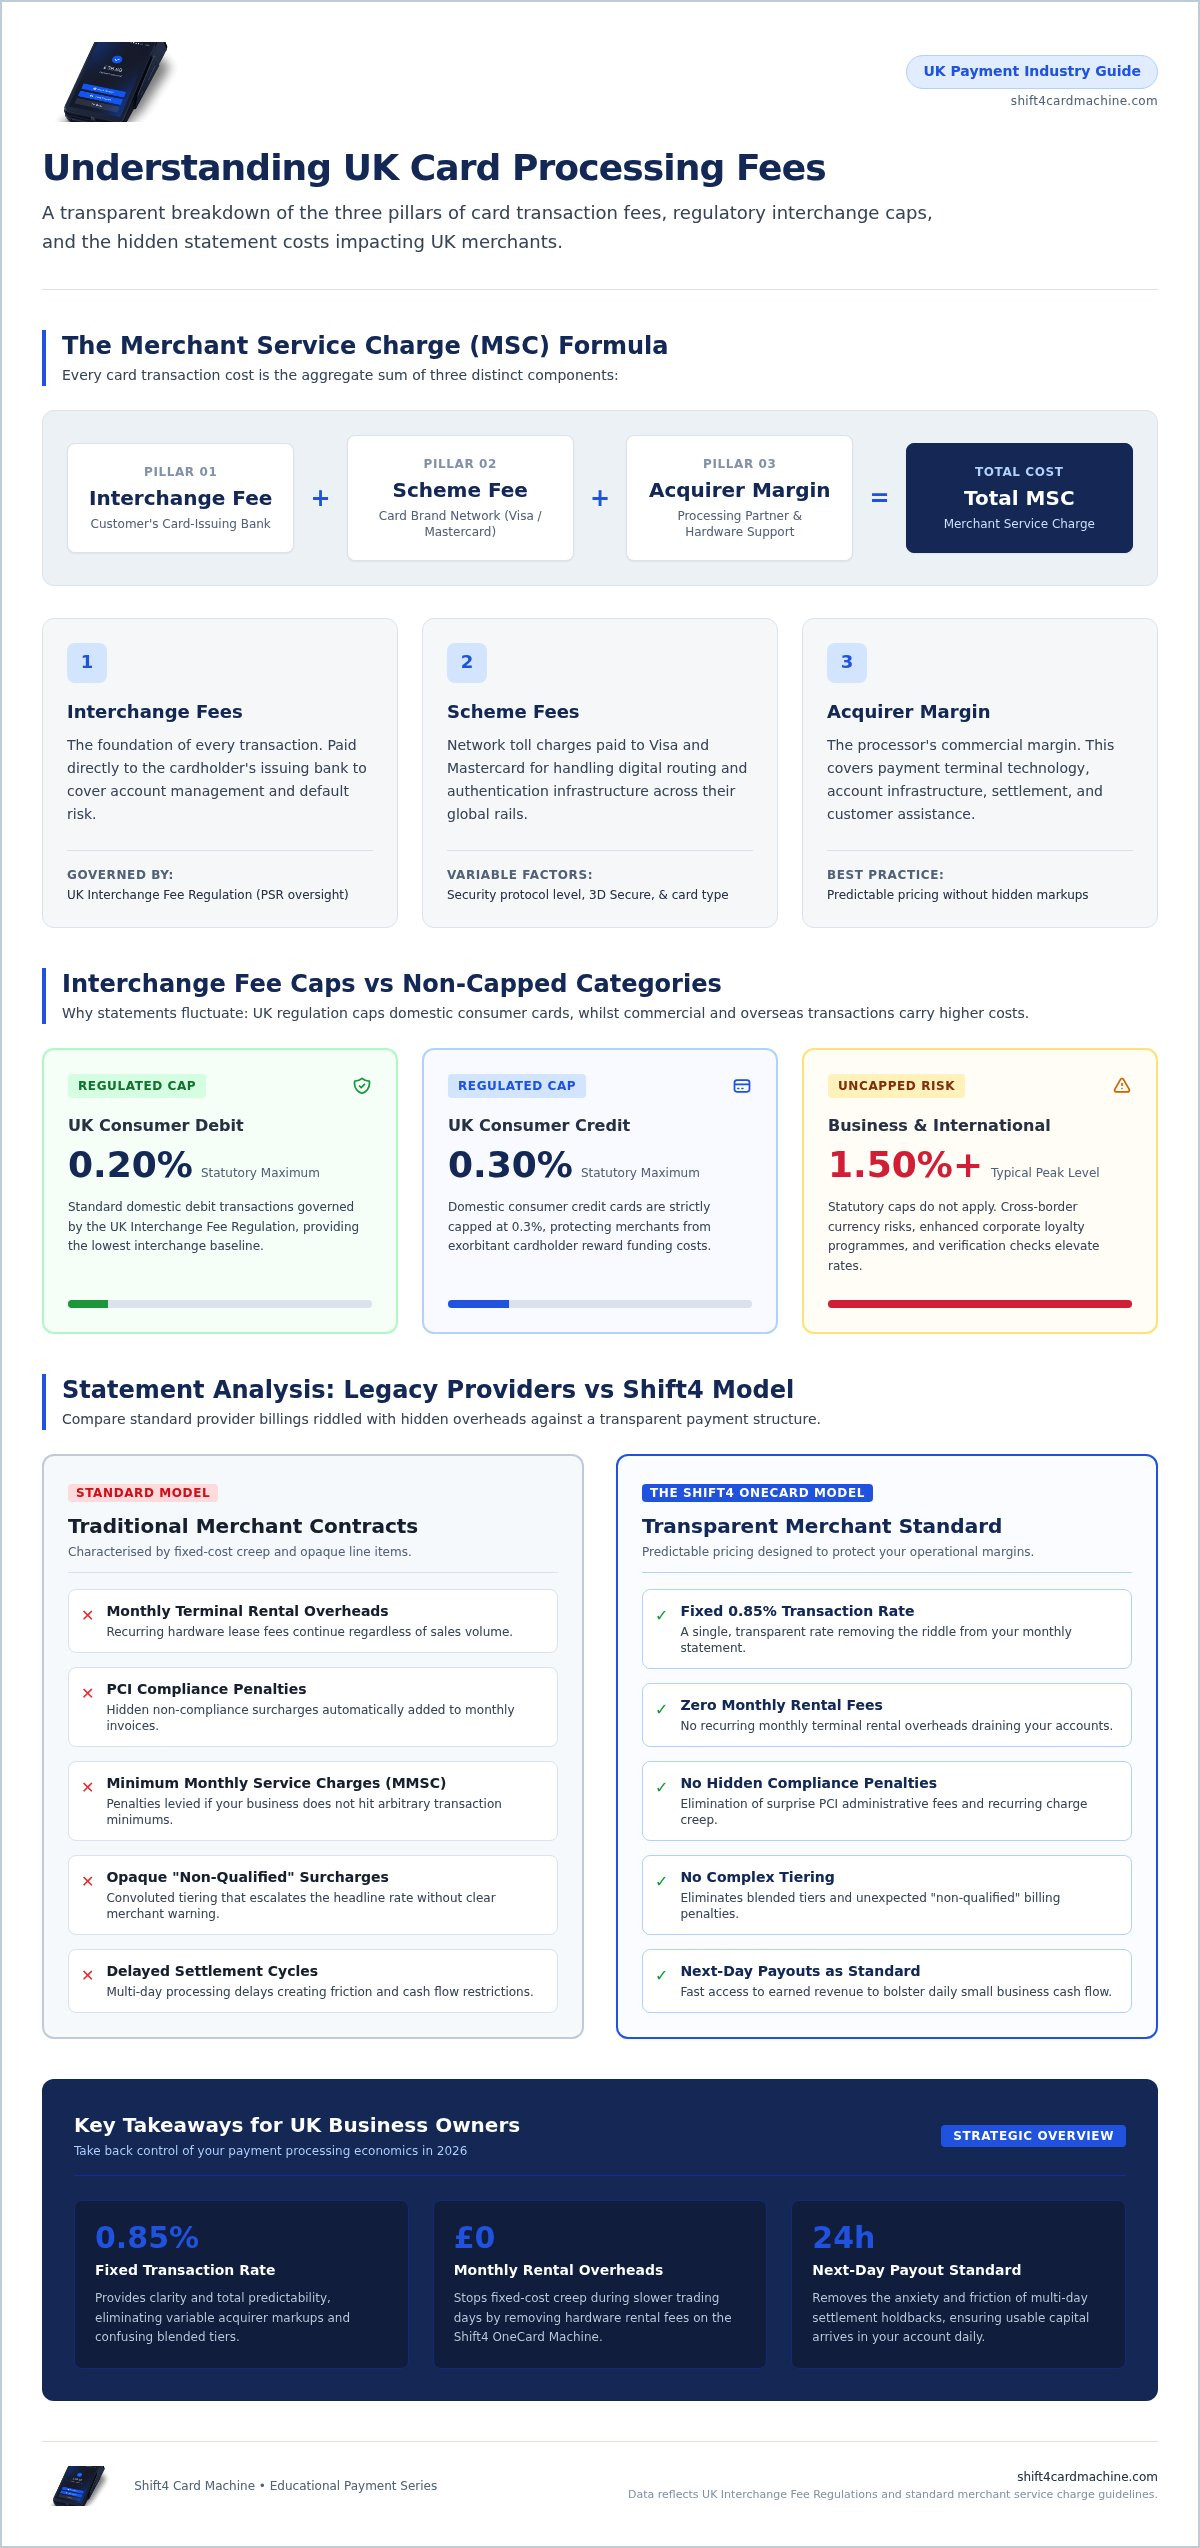
Many providers lure you in with a low headline rate. This is rarely the final price you pay. Your "effective rate" is the true cost of processing once you factor in every hidden surcharge and "non-qualified" fee. Traditional banks typically reward high-volume corporations with better terms, leaving independent businesses to shoulder higher costs. This often leads to "fixed-cost creep." You might see small, recurring charges for PCI compliance or terminal hire that slowly erode your margins. These costs persist regardless of whether you've had a record-breaking Saturday or a quiet Tuesday afternoon. We prefer a simpler path. No monthly rental. No hidden compliance penalties. No complex tiers. The Shift4 OneCard Machine offers a fixed 0.85% transaction rate, giving you total clarity from day one. It's about removing the friction that stops you from growing.
The Three Pillars: Interchange, Scheme, and Acquirer Fees
To get a grip on understanding card processing fees UK, you must look at the three distinct slices taken from every sale. Your total transaction cost isn't one single fee; it is a combination of Interchange, Scheme, and Acquirer charges. Think of it like a journey. The customer's bank, the card network, and your processing partner all take a toll along the way. Your total Merchant Service Charge is simply the sum of these three pillars: Interchange + Scheme + Acquirer.
Interchange: The Foundation of Every Transaction
Interchange is the foundation. It's the fee paid to the customer's bank for the privilege of accepting their card. For most consumer transactions, this is governed by the UK Interchange Fee Regulation, which caps costs at 0.2% for debit and 0.3% for credit. However, these caps don't apply to everything. Business cards and international cards often carry significantly higher costs, sometimes reaching 1.5% or more. International cards are pricier because they involve cross-border currency risks and additional security checks. On a standard statement, these variables are often buried in complex tables, making it nearly impossible to see why one transaction cost more than another. If you see wild fluctuations in your monthly bill, it's usually because the mix of cards your customers use has changed.
Scheme Fees and Acquirer Margins
Next are Scheme fees. These are the "tolls" paid to Visa and Mastercard for using their global networks. They fluctuate based on the security protocol used, such as whether a transaction was fully authenticated with 3D Secure or processed via a mobile wallet. Finally, the Acquirer fee is the margin your payment processor takes. This covers the tech, the support, and the provision of your Shift4 OneCard Machine. Transparency here is vital. The acquirer's margin should be the only part of the fee that feels truly fixed. It pays for the technical infrastructure and the human support you rely on. Many providers hide their own margins behind complex "blended" rates that mask the true cost of cheaper debit transactions. We believe in a different approach. By removing the guesswork, you can focus on your customers whilst we handle the complexity. If you're tired of opaque billing, it might be time to switch to a partner who values honesty as much as you do.
Blended Rates vs Interchange++: Which Model Wins?
Choosing a pricing model is the most critical decision in understanding card processing fees UK. Most providers offer one of two paths. Blended pricing wraps everything into a single percentage. Interchange++ breaks every cost down to its raw components. Both have loyal fans. However, both also carry hidden frustrations that can impact your bottom line. You shouldn't have to choose between simplicity and fair value.
The Pros and Cons of Blended Pricing
Blended pricing feels safe. You know exactly what will be deducted from every sale regardless of whether the customer uses a premium credit card or a standard debit card. It offers total predictability. But there is a catch. This simplicity often hides an "Overpayment Trap." You end up paying high credit card rates for simple debit transactions that should cost significantly less. Many UK startups start here for ease but outgrow the model within six months as they realise they are subsidising their processor's margins. It's a high price to pay for a shorter statement.
Interchange++: The Professional Choice?
Interchange++ is the "cost-plus" model. It offers total transparency by showing exactly what the banks and Visa are taking. You see the raw Payment Systems Regulator guidance on interchange fees in action on every line item. This sounds ideal for savvy business owners who want to see every penny. The reality is often a 10-page monthly statement that requires a degree in finance to decode. It's transparent, yes, but it's also incredibly complex. Most independent businesses don't have the time to audit hundreds of individual transactions every month.
We believe there is a better way. Modern merchant services UK no monthly fee models are disrupting this traditional choice. By offering a fixed 0.85% rate, we provide the simplicity of a blended model without the inflated margins. You get the predictability of one rate for every card type whilst enjoying a price point that respects your hard-earned profits. It's the clarity of a single number combined with the value usually reserved for corporate giants. No complex tables. No hidden surcharges for your favourite card mix. Just honest, transparent pricing that lets you get on with running your business without the financial headache.
Spotting the Hidden "Gotchas" in Your Merchant Statement
Your monthly statement should be a simple record of your success. Instead, it's often a source of confusion and frustration. Many traditional providers use complex layouts to mask a variety of small, recurring penalties. This is where the gap between your headline rate and your actual costs begins to widen. True mastery of understanding card processing fees UK involves looking past the big percentages and identifying the "fixed-cost" traps. These charges persist even when your business is quiet, eating into your hard-earned margins without adding any value to your service.
- PCI DSS Compliance Fees: Many banks charge a monthly "non-compliance" penalty if you haven't jumped through their specific administrative hoops. It is a common revenue stream for processors that punishes busy business owners.
- Minimum Monthly Service Charges (MMSC): This is a penalty for having a quiet month. If your total transaction fees don't hit a specific threshold, the provider charges you the difference. You're effectively paying for sales you didn't even make.
- Authorisation Fees: Often called a "per-click" charge, this is a small fee applied to every transaction attempt. Whilst it might only be a few pence, it adds up rapidly on high-volume days or for businesses with low average transaction values.
- Exit Fees and Long-Term Contracts: Some providers try to lock you into three or five-year deals. If you want to leave for a better offer, they hit you with massive cancellation penalties. We believe your loyalty should be earned, not forced.
Terminal Hire: The Invisible Drain
Hardware costs are one of the most significant hidden expenses in the UK market. Renting a machine for £20 a month might seem affordable at first. However, over a standard three-year contract, that's £720 spent on a device you'll never own. It's an invisible drain on your cash flow. We prefer a "Free Machine" model that removes this monthly overhead entirely. When you use the Shift4 OneCard Machine, you eliminate that rental cost for good. Plus, our lifetime hardware warranty ensures you aren't hit with unexpected repair bills if the tech fails. No rental. No repair costs. Just reliable hardware that works as hard as you do.
Statement and Admin Surcharges
Some "gotchas" are purely administrative. You might still be paying for paper statements or "gateway fees" just to connect your terminal to the processing network. These are outdated charges that have no place in a modern digital economy. If your current provider is still nickel-and-diming you for basic admin, it's a sign they aren't prioritising your growth. You can switch card machine without exit fees and escape these legacy traps. It's about reclaiming your profit and simplifying your life.
Simplifying Your Statement with the Shift4 OneCard Model
Most payment providers profit from your confusion. We profit from your success. Our philosophy is built on a simple negation: no monthly rental, no subscription fees, and no hidden compliance penalties. You only pay when you actually make a sale. This approach transforms the task of understanding card processing fees UK from a monthly headache into a straightforward calculation. When you're committed to understanding card processing fees UK, the conclusion is usually the same: simplicity wins. By setting a fixed 0.85% transaction rate, we provide a competitive benchmark for UK retail and hospitality businesses that value financial clarity. It's a professional-grade solution that respects your margins.
Claiming your free Shift4 OneCard Machine is the first step toward reclaiming your profit. Our application process is designed for speed. Whilst traditional banks might spend weeks vetting a small business, our one-page online application gets you up and running without the red tape. We believe in removing the friction that slows your growth.
Next-Day Payouts: Beyond the Transaction Fee
Speed is just as important as cost. Waiting three to five working days for your money is a hidden cost to your cash flow that can't be ignored. It's your capital; you should be able to use it immediately. A reliable card machine next day payout allows you to restock inventory faster and respond to market demands without delay. Daily settlements provide a sense of security and momentum. You can close your doors at night knowing your hard-earned money will be in your account the very next day. It's about maintaining a steady business rhythm without the anxiety of pending transfers.
The "Jamie" Advantage: Direct Support
We've moved away from the anonymous corporate model. You won't find yourself trapped in a loop of automated call centres or speaking to someone who doesn't understand the UK market. Instead, you get direct, UK-based support from people like Jamie who are personally invested in your success. This human connection is what sets us apart from the clinical giants of the payments industry. Your processing fees should cover more than just technology; they should cover the peace of mind that comes with expert help.
Our lifetime hardware warranty ensures your fees never include "repair costs" or unexpected replacement bills. It's a partnership built on accountability and straightforwardness. You focus on your customers. We'll focus on the tech.
Take Control of Your Transaction Costs Today
Your business deserves a payment partner that works as hard as you do. You've now mastered the essentials of understanding card processing fees UK, from identifying hidden compliance "gotchas" to choosing a simpler, more predictable rate. It's time to stop overpaying for legacy contracts and opaque statements. By eliminating monthly rental overheads and embracing a transparent 0.85% rate, you protect your margins and simplify your daily operations.
Fast-track your growth with next-day payouts as standard. You shouldn't have to wait for your own money whilst your processor holds onto it. With the support of an Authorised Shift4 Partner, you gain a knowledgeable guide who prioritises your success over corporate jargon. It's about building a partnership based on trust, speed, and absolute clarity. No hidden extras. No rental fees. Just honest results.
Take the first step toward a fairer way of working. We're here to help you reclaim your profits and keep your business moving forward with confidence.
Frequently Asked Questions
What is the average card processing fee for small businesses in the UK?
Average fees typically range between 1% and 2.5% depending on your transaction volume and provider. However, understanding card processing fees UK becomes much simpler with a fixed rate model. We offer a transparent 0.85% rate for all transactions. This removes the guesswork. You don't need to worry about complex tiers or fluctuating volume discounts. It provides a stable, predictable benchmark for retail and hospitality businesses across the country.
Is there a difference between debit and credit card processing fees?
Yes, debit cards typically have lower interchange caps compared to credit cards. Under UK regulations, consumer debit is capped at 0.2% and credit at 0.3%. Whilst some providers use this difference to create complex, tiered pricing, we prefer a unified approach. Our 0.85% rate applies across the board for all consumer cards. This ensures you never pay more just because your customer prefers a specific card type. It's about simplicity and fairness.
Can I avoid monthly terminal rental fees in the UK?
You can absolutely avoid monthly terminal rental fees by choosing the right partner. Many traditional banks charge between £15 and £30 per month just to have a machine on your counter. We've eliminated this overhead entirely. The Shift4 OneCard Machine comes with zero monthly rental or subscription costs. You only pay when you make a sale. This removes a significant fixed-cost burden from your monthly business statement and improves your bottom line.
What are PCI compliance fees and are they mandatory?
PCI compliance fees are charges related to the Payment Card Industry Data Security Standard. Whilst maintaining security is mandatory, paying a monthly "non-compliance" fee shouldn't be. Some providers use these fees as a hidden revenue stream to penalise busy merchants. We don't believe in these administrative traps. We help you stay secure without adding extra penalties to your bill. It's a way to ensure security without the unnecessary financial friction.
How much does it cost to switch card machine providers?
Switching providers often involves checking for exit fees in your current contract. These lock-in penalties are designed to stop you from finding a better deal. However, the cost of staying with an expensive provider is usually much higher over time. We make the transition easy by providing the Shift4 OneCard Machine for free. Our simple online application means you can start saving on your understanding card processing fees UK almost immediately without upfront hardware costs.
What happens if I process a transaction from an international card?
International cards often carry higher interchange costs because they involve cross-border processing and currency checks. These transactions are typically exempt from the standard UK fee caps. Most providers pass these high costs directly to the merchant with a significant markup. We maintain transparency in our pricing to ensure you aren't blindsided by your monthly statement. Knowing exactly what to expect helps you manage your international customer base with confidence and clarity.
Are there hidden costs associated with "free" card machines?
Many "free" machines in the industry come with a catch, such as high transaction rates or hidden monthly software subscriptions. We do things differently. Our Shift4 OneCard Machine is genuinely free of rental charges. There are no monthly subscriptions or hidden gateway fees to worry about. You get a professional-grade terminal, a 0.85% fixed rate, and a lifetime hardware warranty. It's a straightforward partnership designed to support your long-term business health.
How quickly can I receive my money after a card sale?
You should receive your money quickly to maintain business momentum. Waiting three to five days for a settlement is a relic of the past that hurts your cash flow. We provide next-day payouts as standard for all our UK merchants. This ensures your hard-earned capital is available when you need it most. Faster access to funds helps you restock inventory and manage daily expenses without the anxiety of long processing delays.
Frequently Asked Questions
Interchange++ is the "cost-plus" model. It offers total transparency by showing exactly what the banks and Visa are taking. You see the raw Payment Systems Regulator guidance on interchange fees in action on every line item. This sounds ideal for savvy business owners who want to see every penny. The reality is often a 10-page monthly statement that requires a degree in finance to decode. It's transparent, yes, but it's also incredibly complex. Most independent businesses don't have the time to audit hundreds of individual transactions every month. We believe there is a better way. Modern merchant services UK no monthly fee models are disrupting this traditional choice. By offering a fixed 0.85% rate, we provide the simplicity of a blended model without the inflated margins. You get the predictability of one rate for every card type whilst enjoying a price point that respects your hard-earned profits. It's the clarity of a single number combined with the value usually reserved for corporate giants. No complex tables. No hidden surcharges for your favourite card mix. Just honest, transparent pricing that lets you get on with running your business without the financial headache. Your monthly statement should be a simple record of your success. Instead, it's often a source of confusion and frustration. Many traditional providers use complex layouts to mask a variety of small, recurring penalties. This is where the gap between your headline rate and your actual costs begins to widen. True mastery of understanding card processing fees UK involves looking past the big percentages and identifying the "fixed-cost" traps. These charges persist even when your business is quiet, eating into your hard-earned margins without adding any value to your service.
Average fees typically range between 1% and 2.5% depending on your transaction volume and provider. However, understanding card processing fees UK becomes much simpler with a fixed rate model. We offer a transparent 0.85% rate for all transactions. This removes the guesswork. You don't need to worry about complex tiers or fluctuating volume discounts. It provides a stable, predictable benchmark for retail and hospitality businesses across the country.
Yes, debit cards typically have lower interchange caps compared to credit cards. Under UK regulations, consumer debit is capped at 0.2% and credit at 0.3%. Whilst some providers use this difference to create complex, tiered pricing, we prefer a unified approach. Our 0.85% rate applies across the board for all consumer cards. This ensures you never pay more just because your customer prefers a specific card type. It's about simplicity and fairness.
You can absolutely avoid monthly terminal rental fees by choosing the right partner. Many traditional banks charge between £15 and £30 per month just to have a machine on your counter. We've eliminated this overhead entirely. The Shift4 OneCard Machine comes with zero monthly rental or subscription costs. You only pay when you make a sale. This removes a significant fixed-cost burden from your monthly business statement and improves your bottom line.
PCI compliance fees are charges related to the Payment Card Industry Data Security Standard. Whilst maintaining security is mandatory, paying a monthly "non-compliance" fee shouldn't be. Some providers use these fees as a hidden revenue stream to penalise busy merchants. We don't believe in these administrative traps. We help you stay secure without adding extra penalties to your bill. It's a way to ensure security without the unnecessary financial friction.
Switching providers often involves checking for exit fees in your current contract. These lock-in penalties are designed to stop you from finding a better deal. However, the cost of staying with an expensive provider is usually much higher over time. We make the transition easy by providing the Shift4 OneCard Machine for free. Our simple online application means you can start saving on your understanding card processing fees UK almost immediately without upfront hardware costs.
International cards often carry higher interchange costs because they involve cross-border processing and currency checks. These transactions are typically exempt from the standard UK fee caps. Most providers pass these high costs directly to the merchant with a significant markup. We maintain transparency in our pricing to ensure you aren't blindsided by your monthly statement. Knowing exactly what to expect helps you manage your international customer base with confidence and clarity.
Many "free" machines in the industry come with a catch, such as high transaction rates or hidden monthly software subscriptions. We do things differently. Our Shift4 OneCard Machine is genuinely free of rental charges. There are no monthly subscriptions or hidden gateway fees to worry about. You get a professional-grade terminal, a 0.85% fixed rate, and a lifetime hardware warranty. It's a straightforward partnership designed to support your long-term business health.
You should receive your money quickly to maintain business momentum. Waiting three to five days for a settlement is a relic of the past that hurts your cash flow. We provide next-day payouts as standard for all our UK merchants. This ensures your hard-earned capital is available when you need it most. Faster access to funds helps you restock inventory and manage daily expenses without the anxiety of long processing delays.
Related articles
Ready for your free machine?
No rental. No catch. Apply in 2 minutes.